 English
Using U.S. Dental Insurance in Mexico: Coverage, Costs, and Dental Tourism in Tijuana
Learn how to use U.S. dental insurance in Mexico: PPO plans, Aetna, MetLife, coverage, Tijuana treatment costs, and payment options.
The Special Teeth · Patient education feature · October 18, 2026
A patient guide to PPO plans, benefits review, regulation, and payment options before traveling.
Your policy, treatment estimate and distance from the dental office belong in the same conversation. Understanding how they work together helps you assess a practical opportunity: receiving dental care in Tijuana, using available benefits and planning treatment you can complete.
Explore the chapters
Introduction
A decision that starts before the border
If you live in the United States and are considering a root canal, crown or implant, your trip to Tijuana can begin with three documents on the table: your diagnosis, an itemized estimate and your dental plan. When those pieces fit together, a lower local fee and benefits valid in Mexico can reduce the amount you need to spend on your oral health.
Figure 1 · AI-generated conceptual photograph
AI-generated conceptual photograph about planning treatment and reviewing coverage.
Related sources
The opportunity comes down to a specific question: what would you pay to complete the same treatment in each country after insurance and all necessary visits? This guide follows that decision from enrollment through follow-up, explaining regulation in both countries, utilization trends and changes that may shape the years ahead.
Dental tourism means traveling internationally to receive dental care. Stoney and Leidel, writing in the CDC Yellow Book 2026, identify it as the most common form of medical tourism among US residents. For people near the border, that journey can be planned around both treatment and follow-up (Stoney & Leidel, 2025).
Understanding Tijuana’s role starts with the relationship between the city and patients who live on the other side of the border. Continue
Background
A city within a cross border routine
For residents of San Diego and Southern California, Tijuana’s proximity can make consultations, adjustments and checkups practical. A shared language, cultural familiarity or family connections can also support communication during a healthcare decision. That proximity becomes more valuable when it allows you to return to the same team and complete your care.
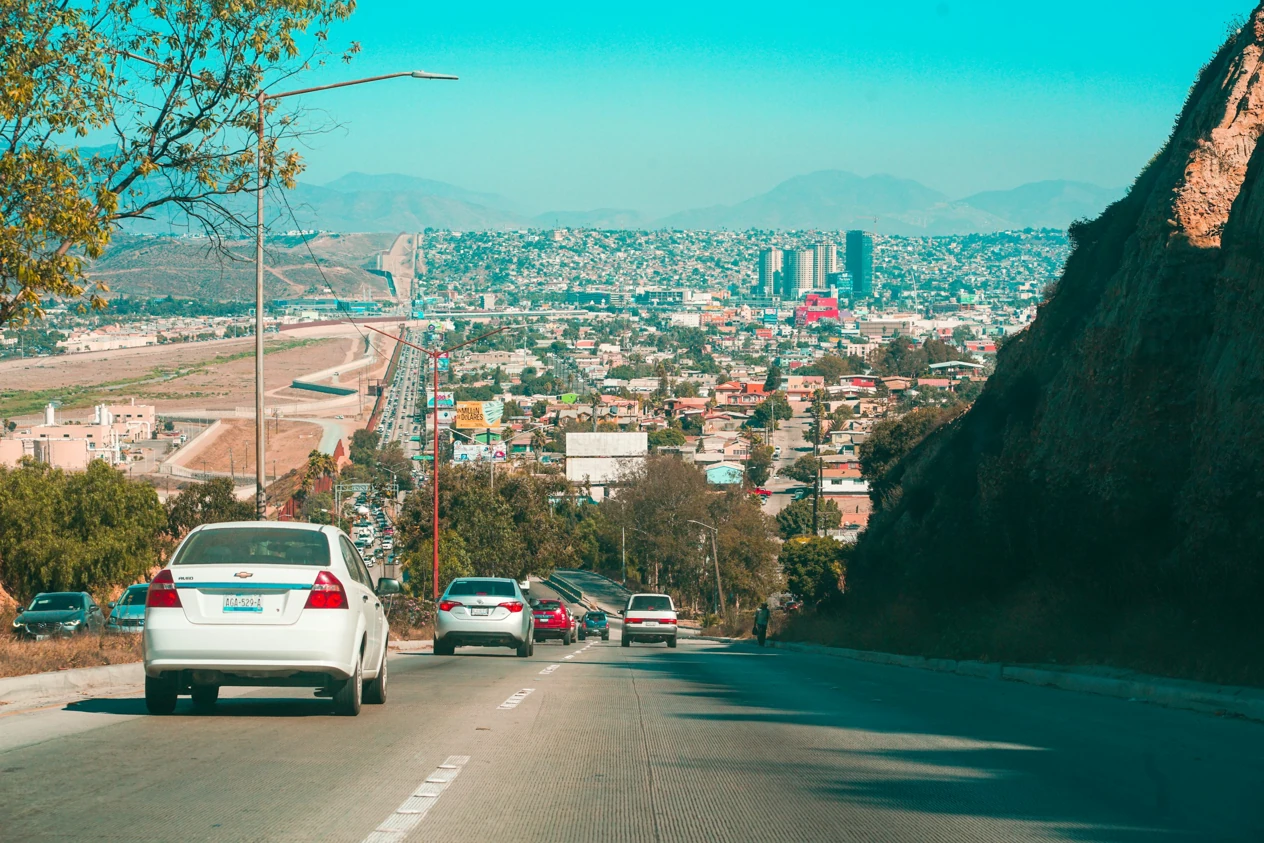
Figure 2 · Stock photograph
Urban view of Tijuana. Photograph by Barbara Zandoval on Unsplash, published in 2021; destination context image.
Barbara Zandoval · Photograph source
Related sources
Ramos and Cuamea studied 384 returning dental tourists in Tijuana. Price, service quality, cultural proximity and supporting services were associated with their intention to return. The research examines that group’s perceptions and decisions, offering insight into why the overall experience matters when patients choose a destination (Ramos & Cuamea, 2023).
Mexico’s Secretariat of Tourism includes medical or health tourism in action line 4.2.5 of its Tourism Sector Program 2025–2030. Baja California’s Tourism Sector Program 2022–2027 also recognizes the segment’s potential. These policies place care for visitors within regional development and help explain cooperation between healthcare, transport and accommodation services (Secretaría de Turismo, 2025; Secretaría de Turismo de Baja California, 2022).
Location helps make the trip possible. The next part of the decision is the economy behind the treatment fee. Continue
Discussion
01 Why dental treatment can cost less in Mexico
A dental appointment brings together professional time, support staff, premises, laboratory work, supplies and equipment. Those inputs are purchased in different local markets. The Organisation for Economic Co-operation and Development (OECD) explains that healthcare services are largely produced where patients receive them, with prices related to wages and the broader price level of each economy (OECD, 2025).
That structure helps explain how a Mexican practice can offer a lower fee for a procedure also performed in the United States. Applied to the border, this is an economic interpretation: local operating costs can support competitive pricing. The size of that advantage needs to be checked in each practice’s estimate. The OECD report compares healthcare systems and does not calculate savings on a crown in Tijuana.
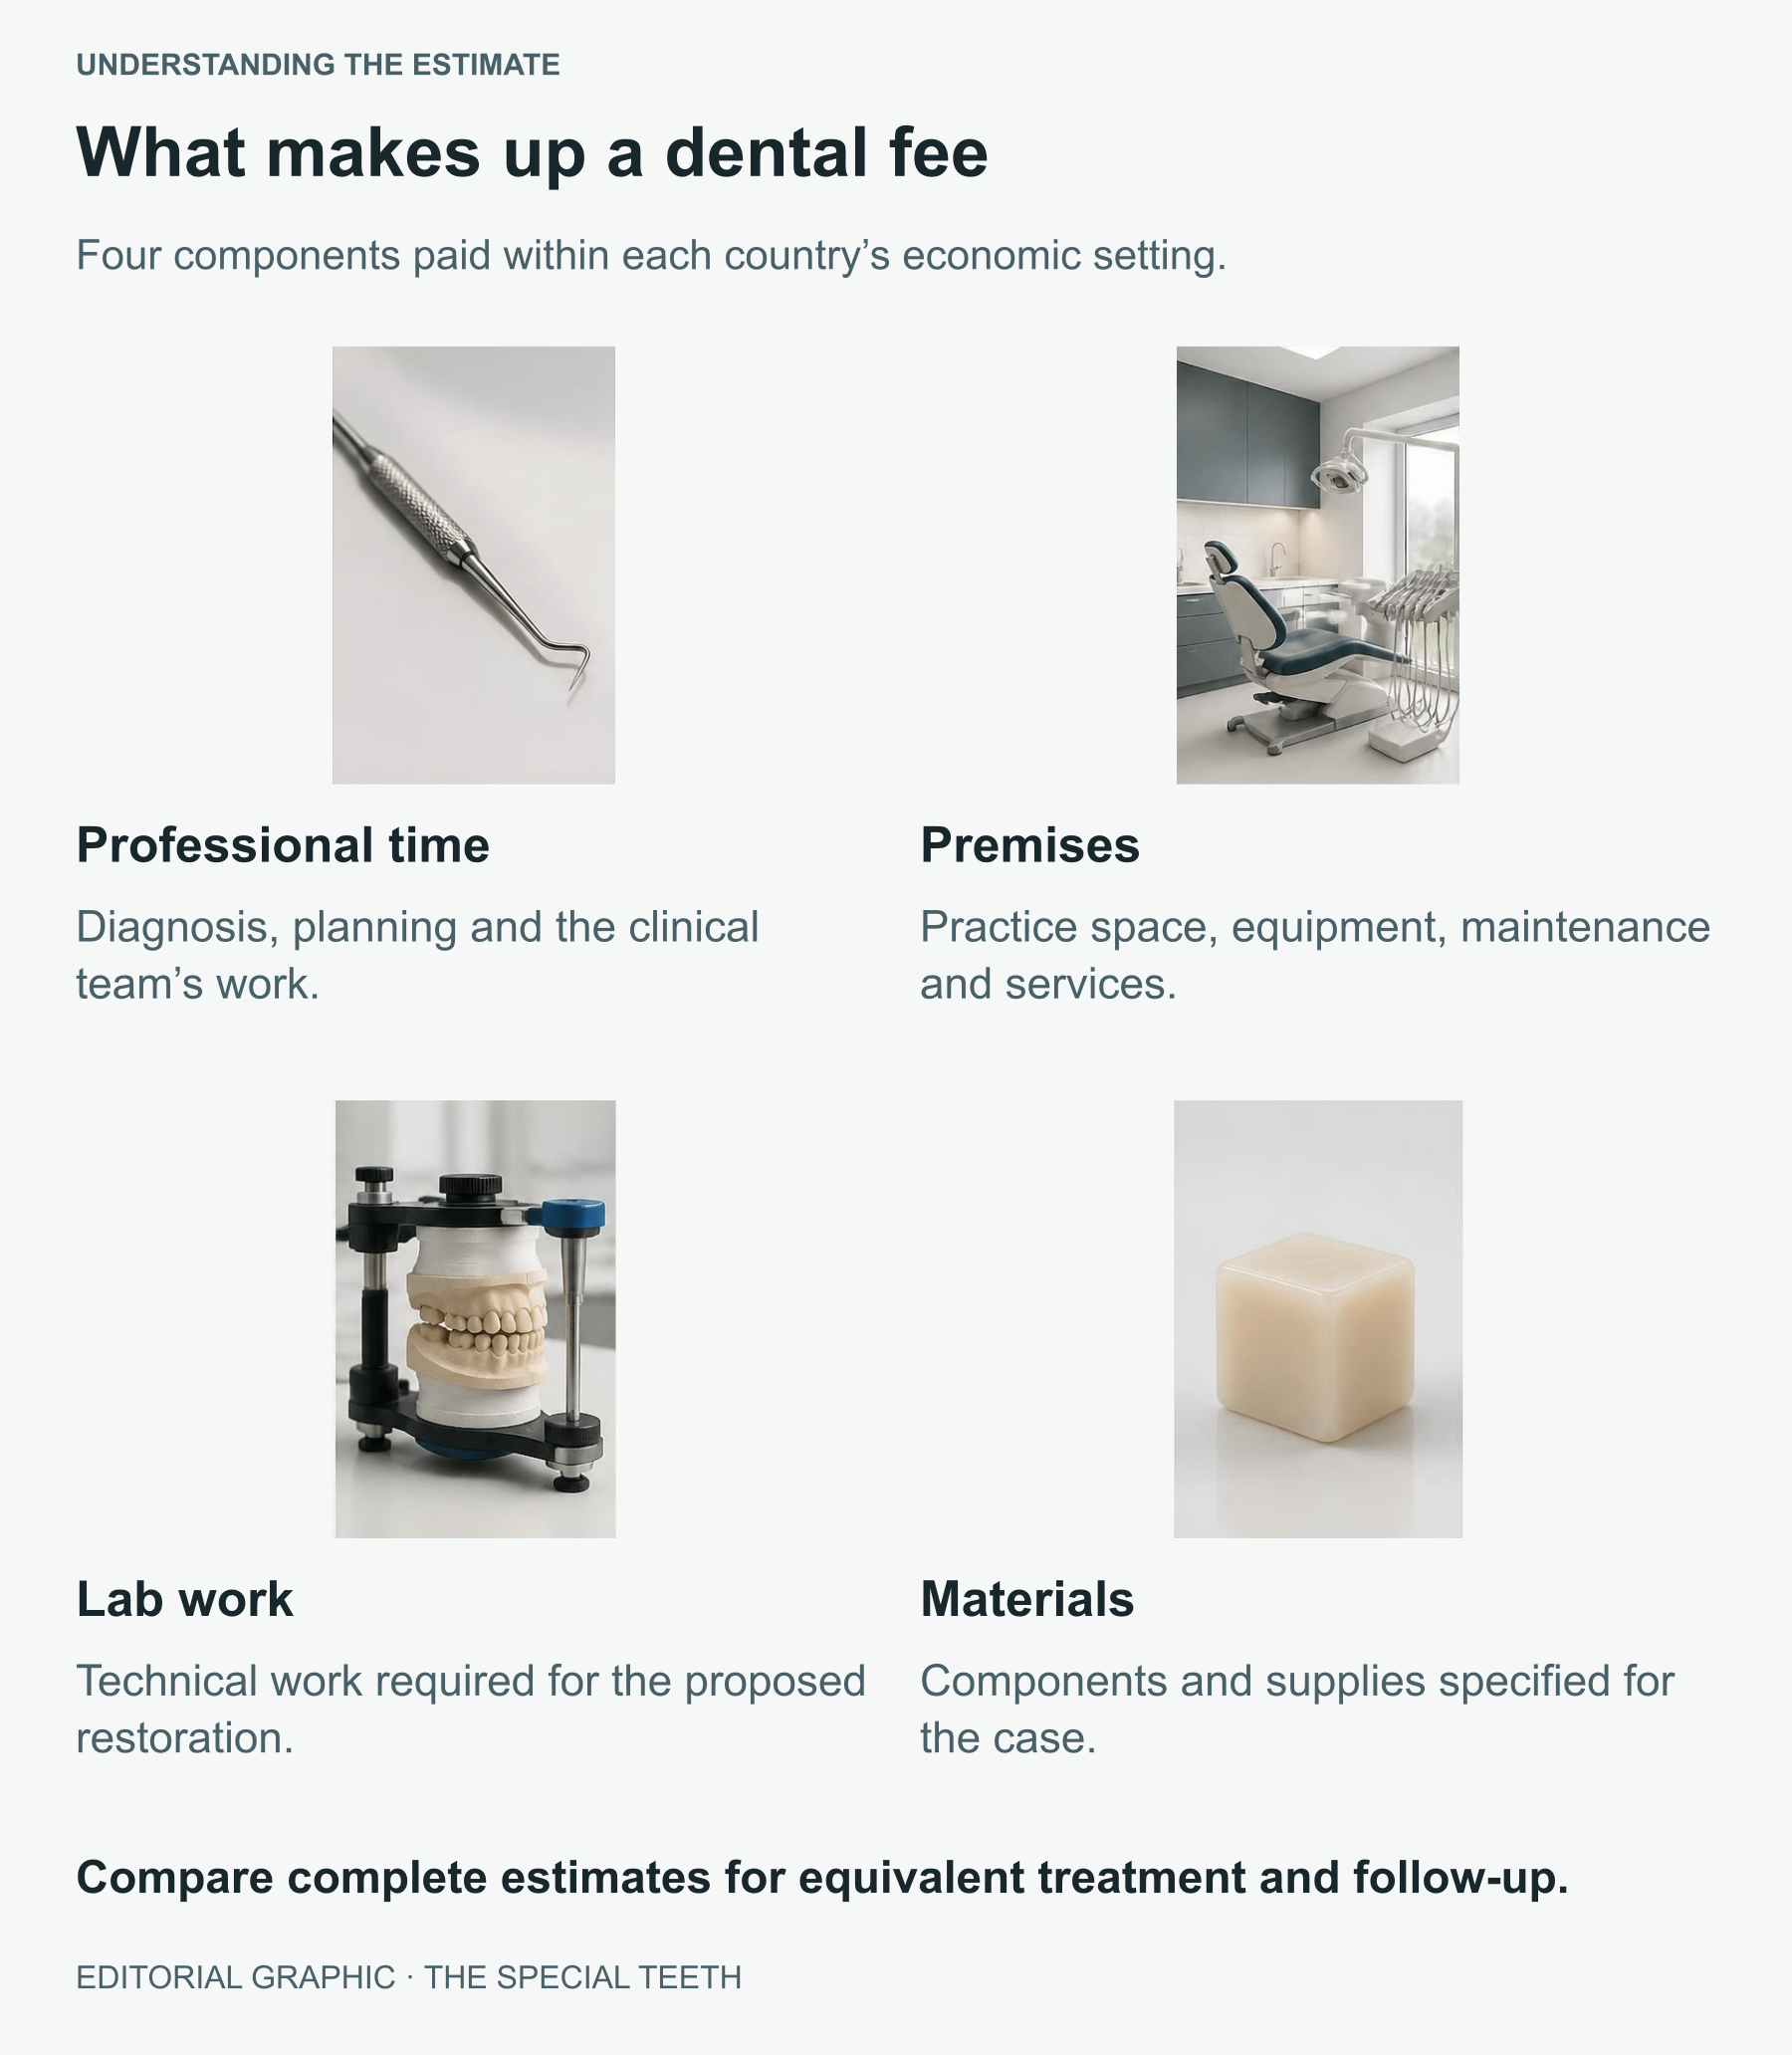
Figure 3 · Editorial graphic
Local costs help explain pricing differences; an individual estimate establishes the amount for your case.
Related sources
In the United States, Bertram Hughes of the American Dental Association’s (ADA) Council on Dental Benefit Programs describes the pressure that wages, supplies, equipment, rent, continuing education and compliance place on practice operating costs. His 2026 discussion provides context for US dental fees (American Dental Association, 2026b).
For a patient, the value emerges when an accessible fee comes with a clear diagnosis and a well-defined procedure. Ask which restorative material will be used, which laboratory is involved, what relevant experience the clinician has and how follow-up will work. Those details let you evaluate the proposal from the practice that will actually provide your care.
With that explanation in mind, published prices provide a starting point for a more concrete comparison. Continue
02 Dental costs in the United States and Tijuana: how to compare
The references below show the difference in scale between US fees and prices advertised by The Special Teeth. All amounts are in US dollars, before any insurance benefits.
| Procedure | US reference | The Special Teeth in Tijuana |
|---|---|---|
| Root canal treatment | National average US$978; range US$679–1,733 | Published price US$300 |
| Dental crown | Porcelain: average US$1,399; range US$915–3,254 | Zirconia: from US$450 |
Kennedy reports the root canal figures using ASQ360° research commissioned by CareCredit in 2025–2026; Rosenfeld reports crown figures using 2024 data. These are commercial US cost studies. The Tijuana amounts are one practice’s advertised prices, checked on October 17, 2026 (Kennedy, 2026; Rosenfeld, 2024; The Special Teeth, n.d.-b).
To compare your own case, match the tooth, complexity, material and included services. The US porcelain category and the zirconia crown advertised in Tijuana have different descriptions. National price references also differ from your PPO’s negotiated fees. An individual comparison therefore requires two itemized estimates.
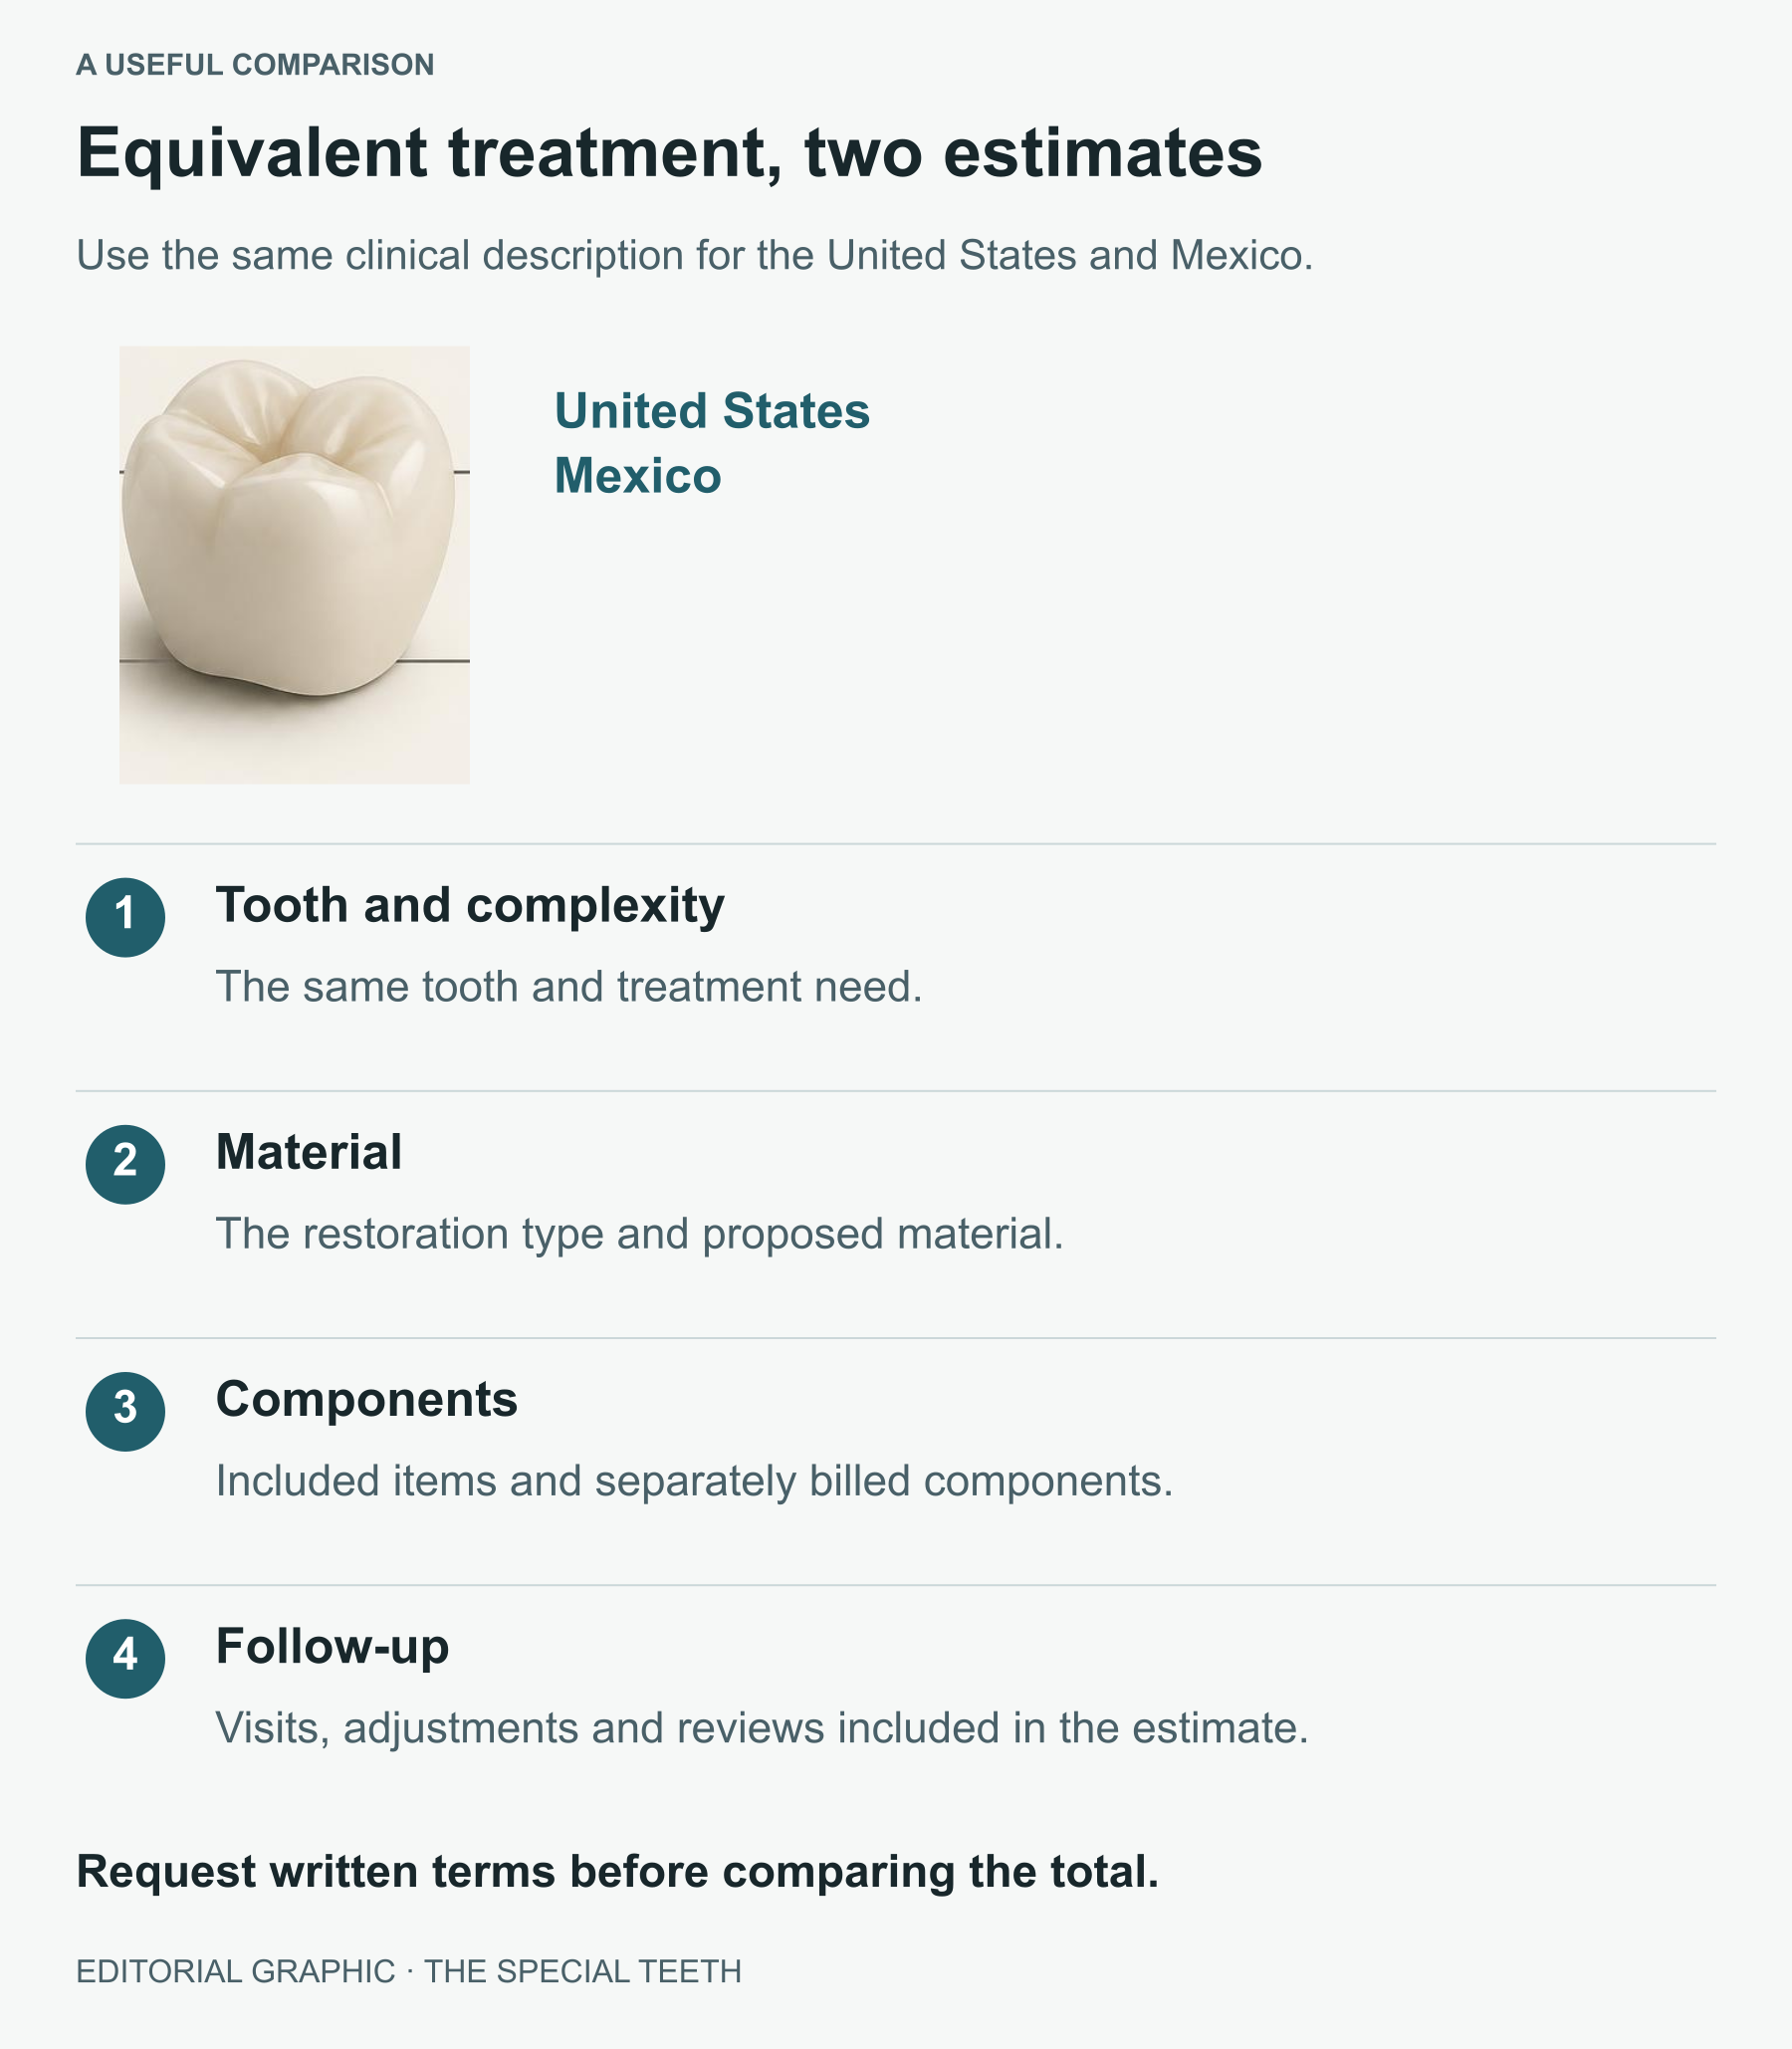
Figure 4 · Editorial graphic
A useful comparison matches the tooth, complexity, material, components and follow-up.
Related sources
Root canal treatment may require a separately charged buildup and final restoration. A complete implant restoration may include implant placement, an abutment and a crown, plus imaging or grafting if indicated. The Special Teeth’s home page advertises an implant from US$1,000 and specifies that this is for the implant fixture only. Each estimate should identify the stage you are paying for (The Special Teeth, n.d.-b).
Once you understand what the fee includes, you can find out which part your dental plan recognizes. Continue
03 What dental insurance is and what your premium pays for
Dental insurance is a contract specifying which oral healthcare services receive financial support, under what conditions and within which limits. In exchange for a recurring premium, the insurer pays the share defined in the policy. In a self-funded employee benefit program, the employer may fund benefits and hire a company to administer them. Your plan documents identify who is responsible (MetLife, 2026c; American Dental Association, n.d.-a).
These arrangements spread expenses across members or an employee benefit program and organize payment for preventive care and treatment. Coverage can help you budget for checkups and reduce spending on included services. Its usefulness depends on benefits you can actually access: annual premiums, expected treatment, network rules, deductibles and available coverage.
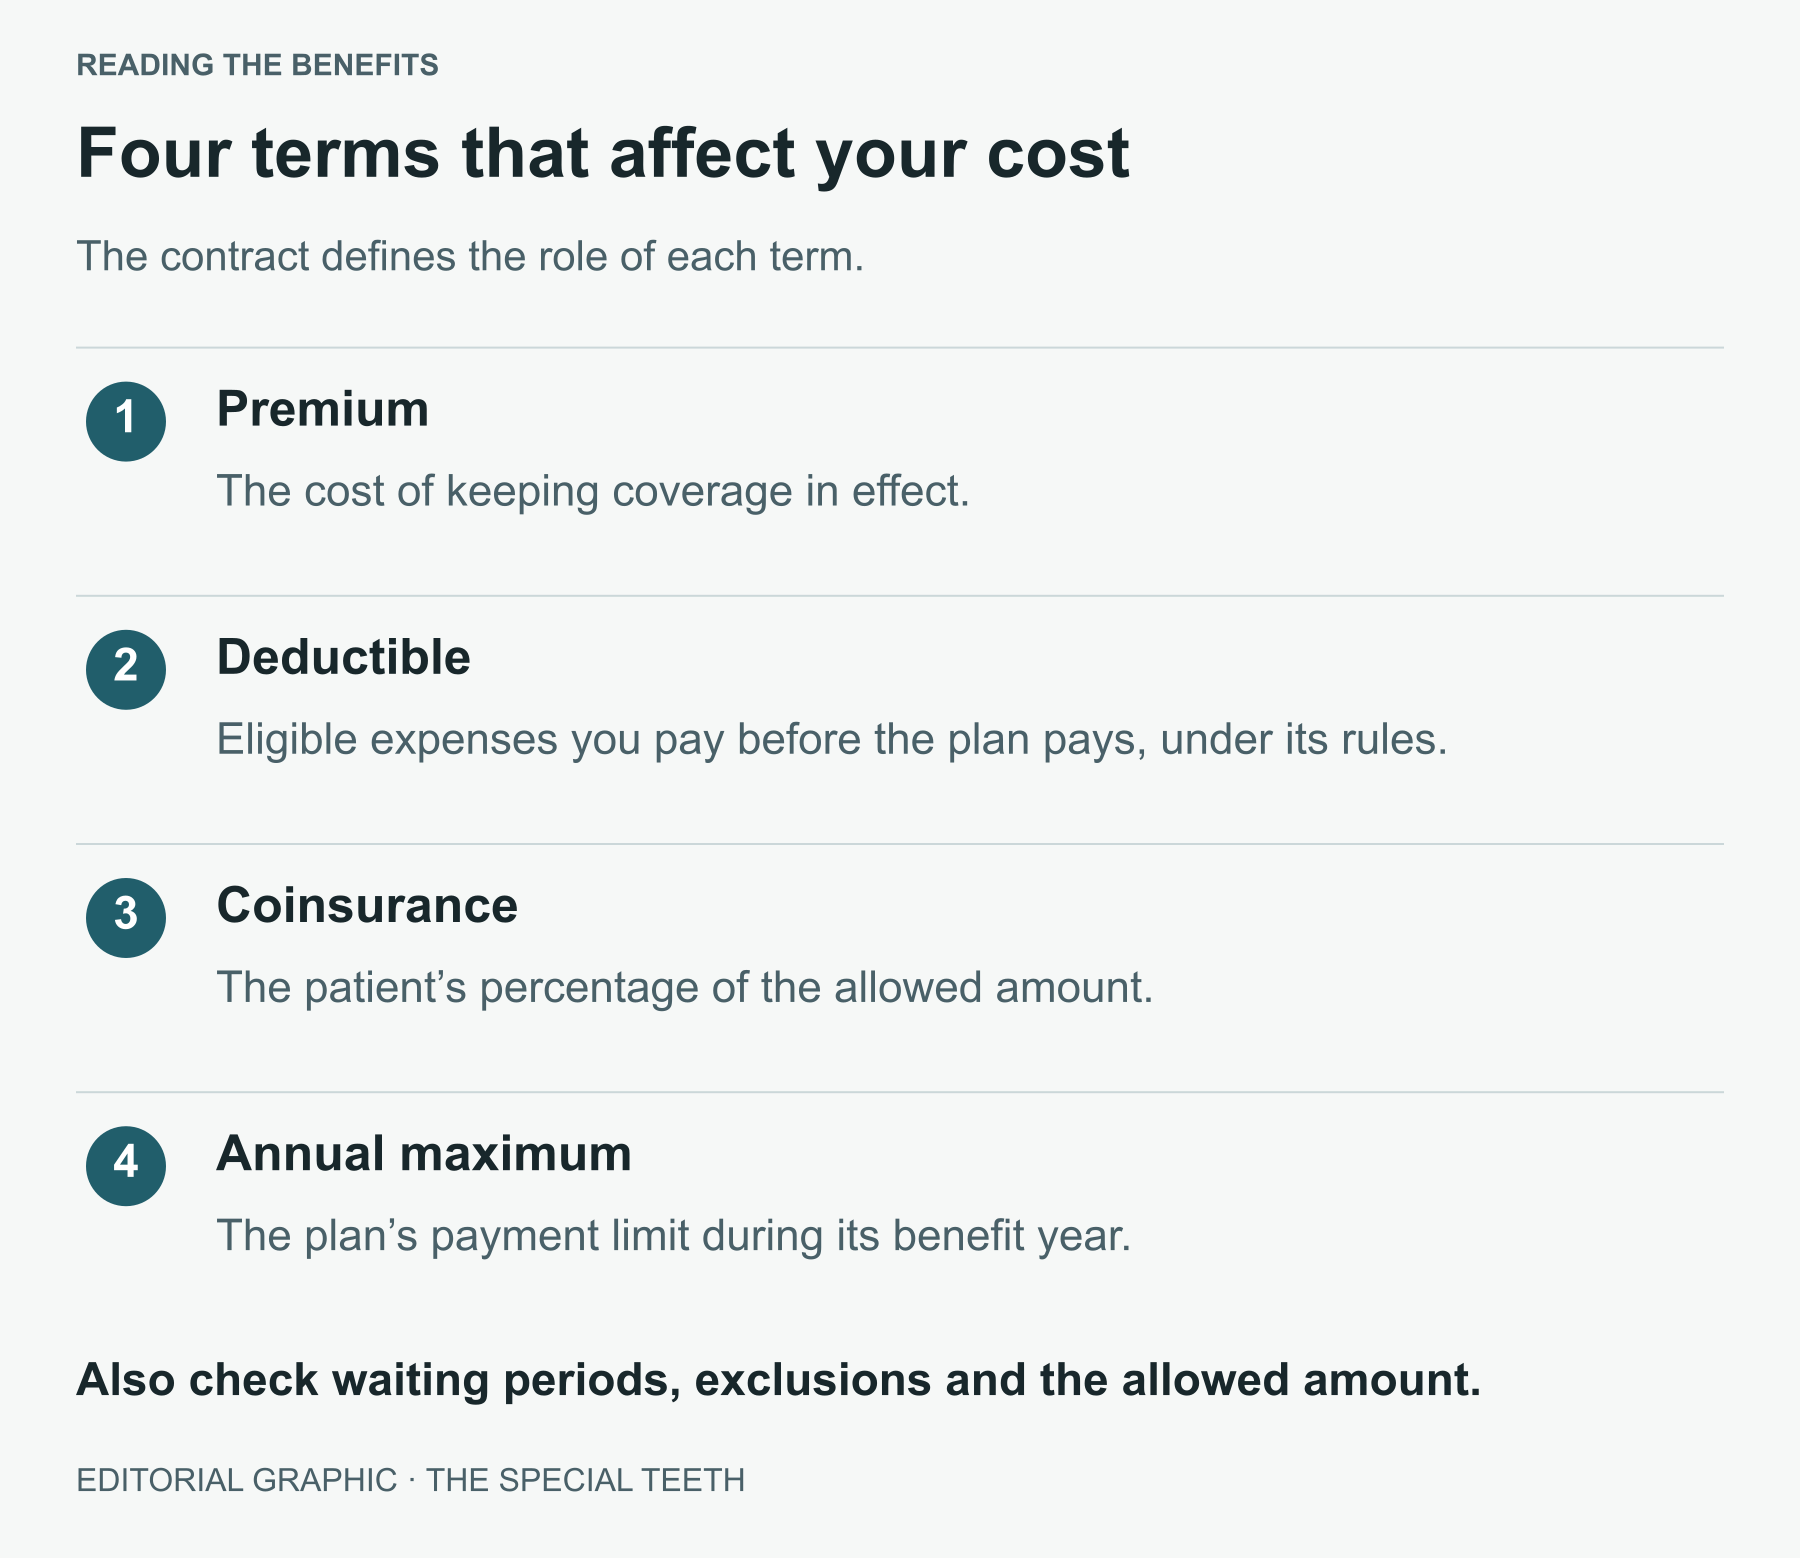
Figure 5 · Editorial graphic
Premiums, deductibles, coinsurance and annual maximums play different roles in calculating benefits.
Related sources
Dental coverage is often purchased separately from medical coverage. HealthCare.gov distinguishes dental benefits included in a health plan from separate dental plans. When enrolling, check that the documents include dental care for your age group and for the family members you want to cover (Centers for Medicare & Medicaid Services, n.d.).
It also helps to understand the roles of clinical and benefit decisions. Your dentist recommends options based on your diagnosis; the administrator applies plan provisions to the services claimed. Clinically indicated treatment can still leave you with an amount to pay. Understanding that relationship helps you make decisions with the full budget in view.
How those costs are shared depends on the plan’s design. The initials on your card offer the first clue. Continue
04 PPO and DHMO: differences when choosing a dentist
A PPO, or Preferred Provider Organization, combines dental coverage with a network of dentists who agree to fees. It may also include out-of-network benefits, subject to the contract. That flexibility makes it relevant to check whether the plan permits scheduled treatment in Mexico (MetLife, 2025c).
| Plan design | How care is organized | What to check for Mexico |
|---|---|---|
| PPO or DPPO | Negotiated network fees; may pay outside the network | Territorial provisions and out-of-network calculation |
| DHMO or DMO | Assigned dentist or practice and service copays | Whether an authorized Mexican network exists |
| EPO | Benefits concentrated on participating providers | Whether your dentist belongs to that network |
| Indemnity | Procedure benefits paid by percentage or schedule | Covered territory and recognized amount |
| POS | An option to leave a network under specific rules | Benefits available outside that network |
| Employer direct reimbursement | Support based on dental spending under program rules | Receipts, limits and international care |
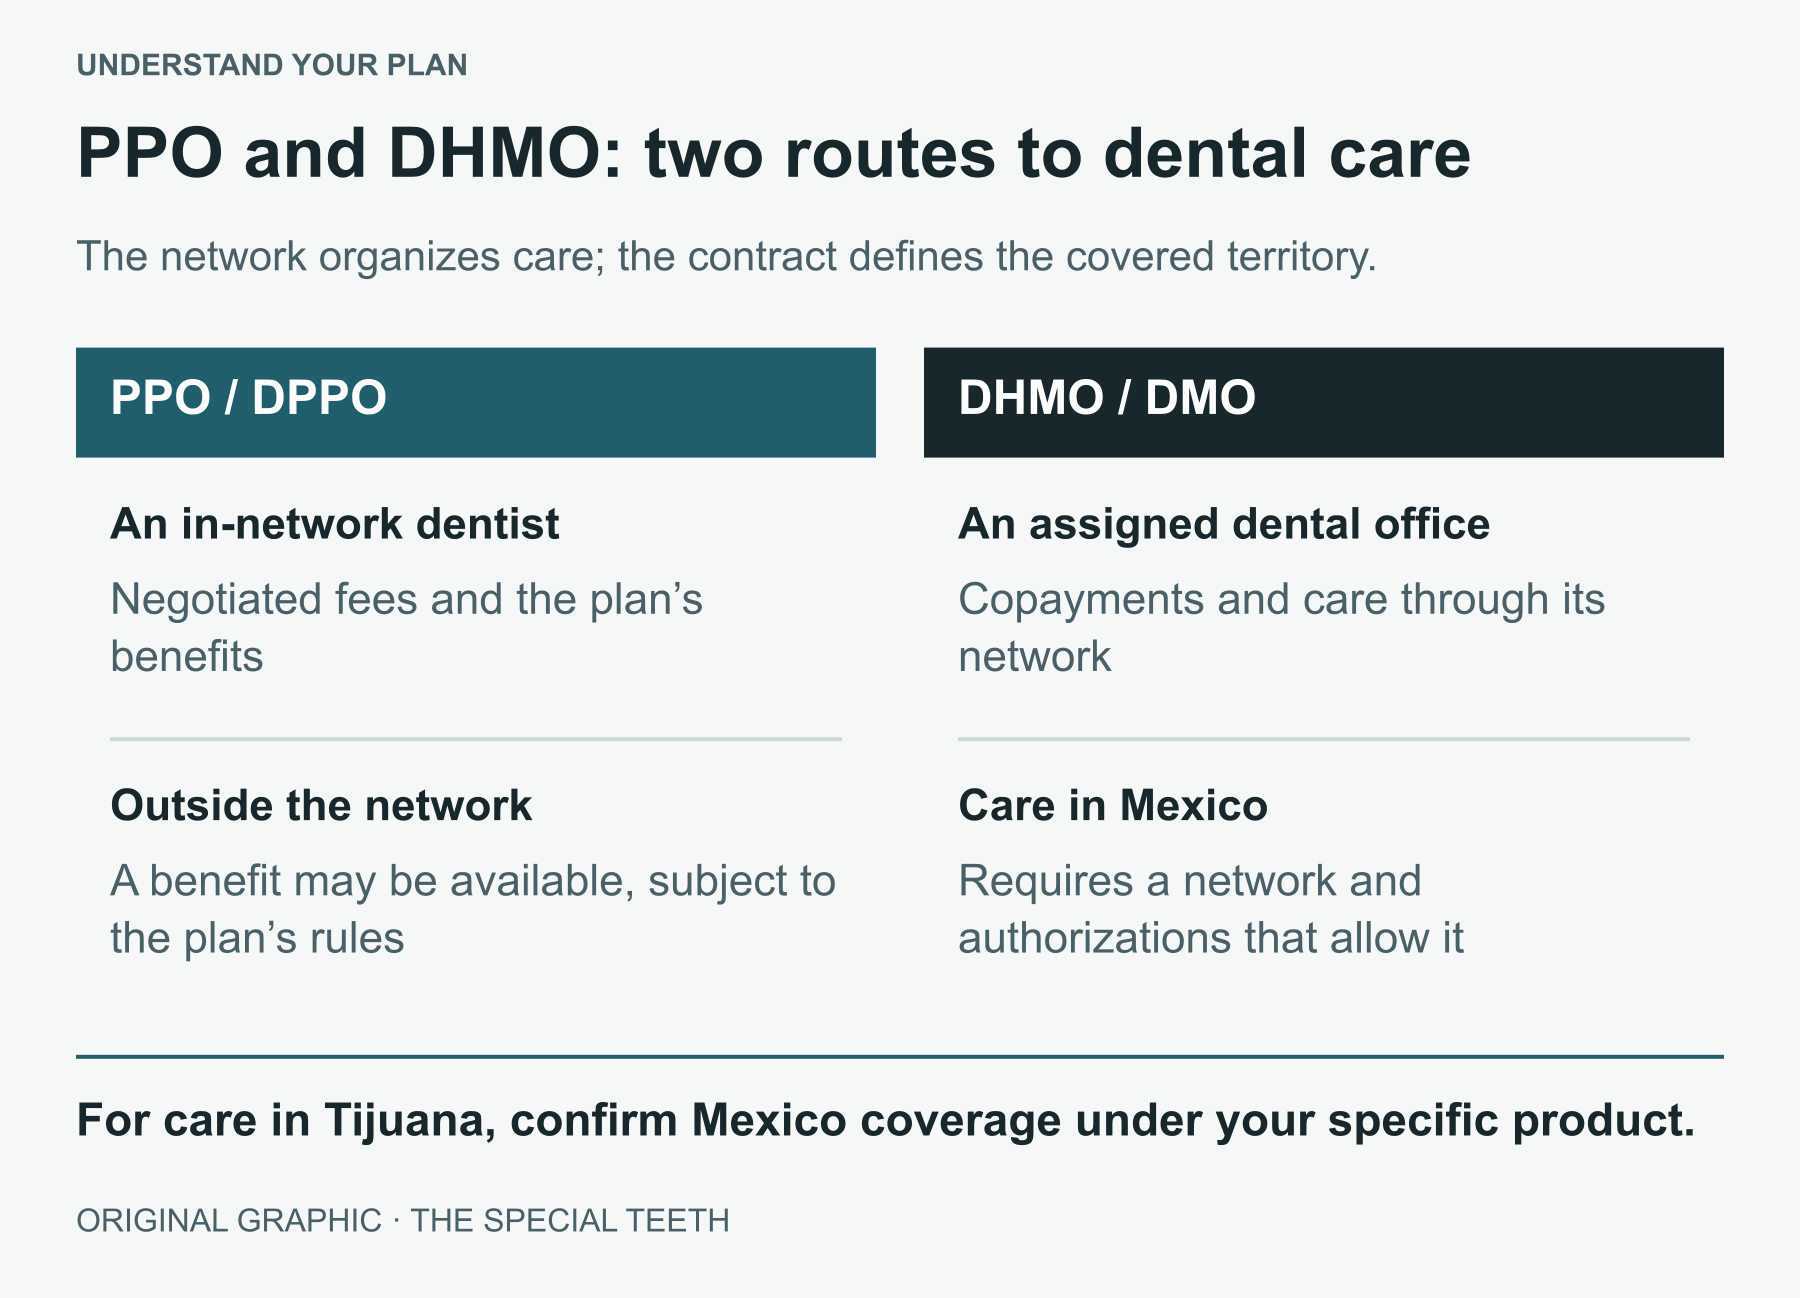
Figure 6 · Editorial graphic
These routes summarize product design. Territorial provisions determine whether care in Mexico is eligible.
Related sources
(American Dental Association, n.d.-b; MetLife, 2025b; MetLife, 2025c)
The American Dental Association describes these arrangements alongside discount memberships, which provide agreed prices while the member pays for treatment. To use a membership in Tijuana, the practice must participate in that program (American Dental Association, n.d.-b).
A DHMO generally organizes care through an assigned dentist and referrals. MetLife describes a DHMO product with copays, no deductible and no annual maximum; those terms belong to that product. Cross-border programs also exist: SIMNSA’s 2026 documents address dental benefits for members who have selected that option, subject to its rules and authorizations (MetLife, 2025b; SIMNSA, 2026).
The next step is finding out how you can obtain the right plan for your circumstances and what it costs to maintain. Continue
05 How to get dental insurance in the United States
At work, contact Human Resources when you are hired or during enrollment. Your employer may contribute toward premiums and deduct the balance from your paycheck, or offer a voluntary benefit funded by employees. Ask for the amount per pay period and convert it into an annual total when comparing options (MetLife, 2026a).
Figure 7 · AI-generated conceptual photograph
AI-generated conceptual photograph about reviewing employer dental benefits.
Related sources
If you are self-employed, have changed jobs or need an individual policy, you can apply directly to an insurer or through a licensed agent. An agent can help compare products; availability depends on your state, residence and the plan’s requirements. For care in Mexico, ask for the international coverage answer to be supported by the contract.
As starting references, Aetna advertises Dental Direct DMO from US$17 per month, Core PPO from US$22, Preferred PPO from US$26 and Preferred 2000 PPO from US$29. These are its published lowest rates, subject to location, product and people covered. Cigna advertises plan categories with average monthly premiums starting at US$19 and US$44, using rates dated July 2025. You need a quote for your own address (Aetna, n.d.; Cigna Healthcare, n.d.).
Before purchasing, check the effective date and any waiting period: the time you must be enrolled before specified services become eligible. Aetna’s page describes waits of 6 to 12 months for basic or major care and prior-coverage waiver rules. Buying today and receiving a crown tomorrow requires confirmation that the procedure is already eligible (Aetna, n.d.).
HealthCare.gov explains that a separate dental plan on the federal Marketplace is purchased while enrolling in a medical plan; state marketplaces may have different rules. Public and employment programs also set eligibility requirements. Original Medicare excludes routine dental care, with exceptions linked to covered medical treatment; Medicare Advantage may offer dental benefits that require their own review (Centers for Medicare & Medicaid Services, n.d.; Centers for Medicare & Medicaid Services, 2026b).
Premiums help you compare options. The exact product name tells you which coverage you are comparing. Continue
06 Aetna and MetLife dental: PPO, PDP Plus and coverage
Aetna and MetLife offer or administer dental products. Each can have different coverage for employees, individual buyers and federal program members. Look for the plan type, group number and product name on your card and certificate. Those details allow a benefits representative to consult the correct terms.
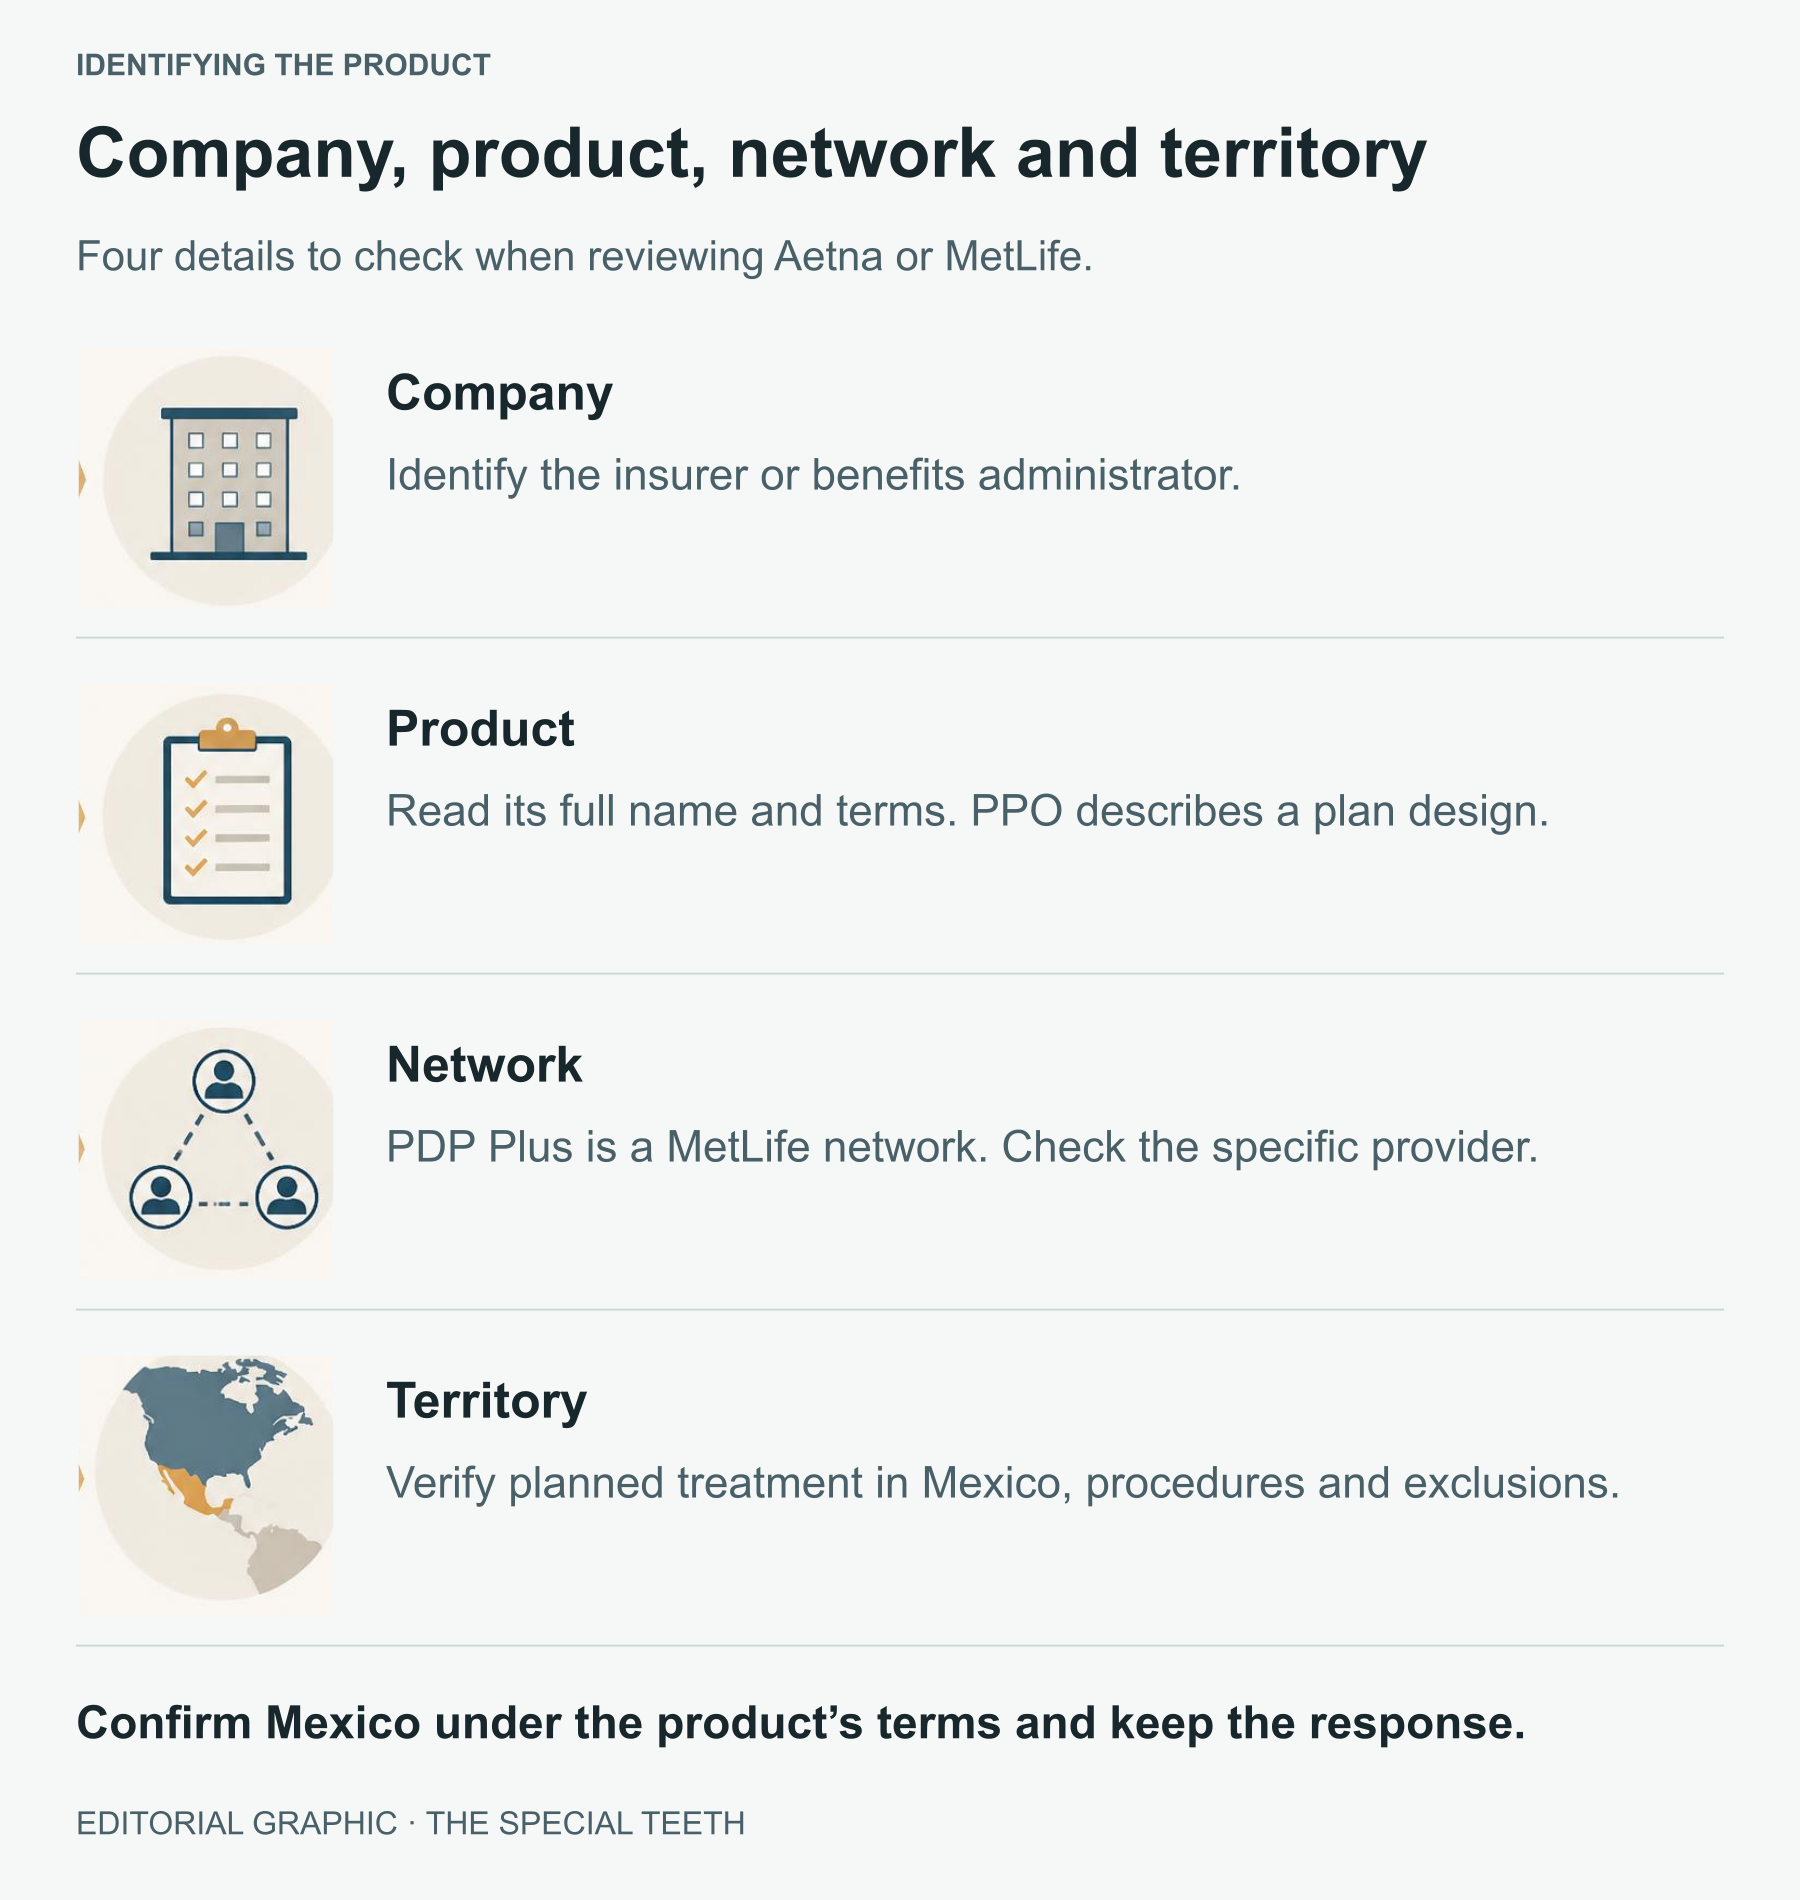
Figure 8 · Editorial graphic
Aetna and MetLife have different products; company and network names help identify the applicable contract.
Related sources
Aetna and documented international coverage
Aetna International’s November 2023 dental PPO flyer describes visiting licensed dentists outside the United States, paying for care and requesting reimbursement. The Aetna Dental FEDVIP 2026 contract also includes international services and explains that this product has no participating network outside the country. Both provide documented examples of international benefits within specific products (Aetna, 2023; Aetna, 2026).
Dental Direct has its own PPO and DMO options. An individual policyholder needs to review territorial terms even after reading that a different Aetna product pays for care abroad.
MetLife PPO and the PDP Plus network
In MetLife’s dental materials, PPO identifies a coverage design and PDP Plus identifies a provider network. If you have heard a name such as “MetLife Pro,” check the card and certificate for the actual product and network names. PDP Plus participation and permission to receive care in Mexico need separate confirmation (MetLife, 2025c).
MetLife also offers TakeAlong Dental for individual enrollment, with options based on residence. Individual and employer plans can have different provisions. Before purchasing coverage for a dental trip, request the territorial exclusions and benefits of the exact product you would receive (MetLife, n.d.).
MetLife’s FEDVIP 2026 brochure includes an international services section and reimbursement process. Its benefit provisions for international participants must be read within that program. If you live in the United States and travel to Tijuana, ask which benefit applies to your circumstances (MetLife, 2026b).
Once you identify the product, you can move from a general insurance question to an answer about your treatment. Continue
07 How to use US dental insurance in Mexico
Ask specifically whether your plan pays for scheduled dental treatment in Mexico with your chosen clinician at the actual treatment address. Emergency care during a vacation may be governed by different terms from a planned restoration. The answer needs to match your product, member status and treatment dates.
- Does the contract permit these procedures in Mexico, and which territorial exclusions apply?
- What percentage and allowed amount will apply to each procedure and material?
- Which deductible, remaining maximum, waiting period and frequency limits apply?
- Is prior authorization required, or can the plan issue a pretreatment estimate?
- Who receives payment, and what documents, currency and filing deadline are required?
Request a written answer and keep the inquiry reference number. If the plan needs a pretreatment submission, a diagnosis, procedure codes and itemized fees support a more precise review. A predetermination estimates benefits using available information; eligibility, completed services and current provisions are checked when the claim is processed (American Dental Association, 2026a).
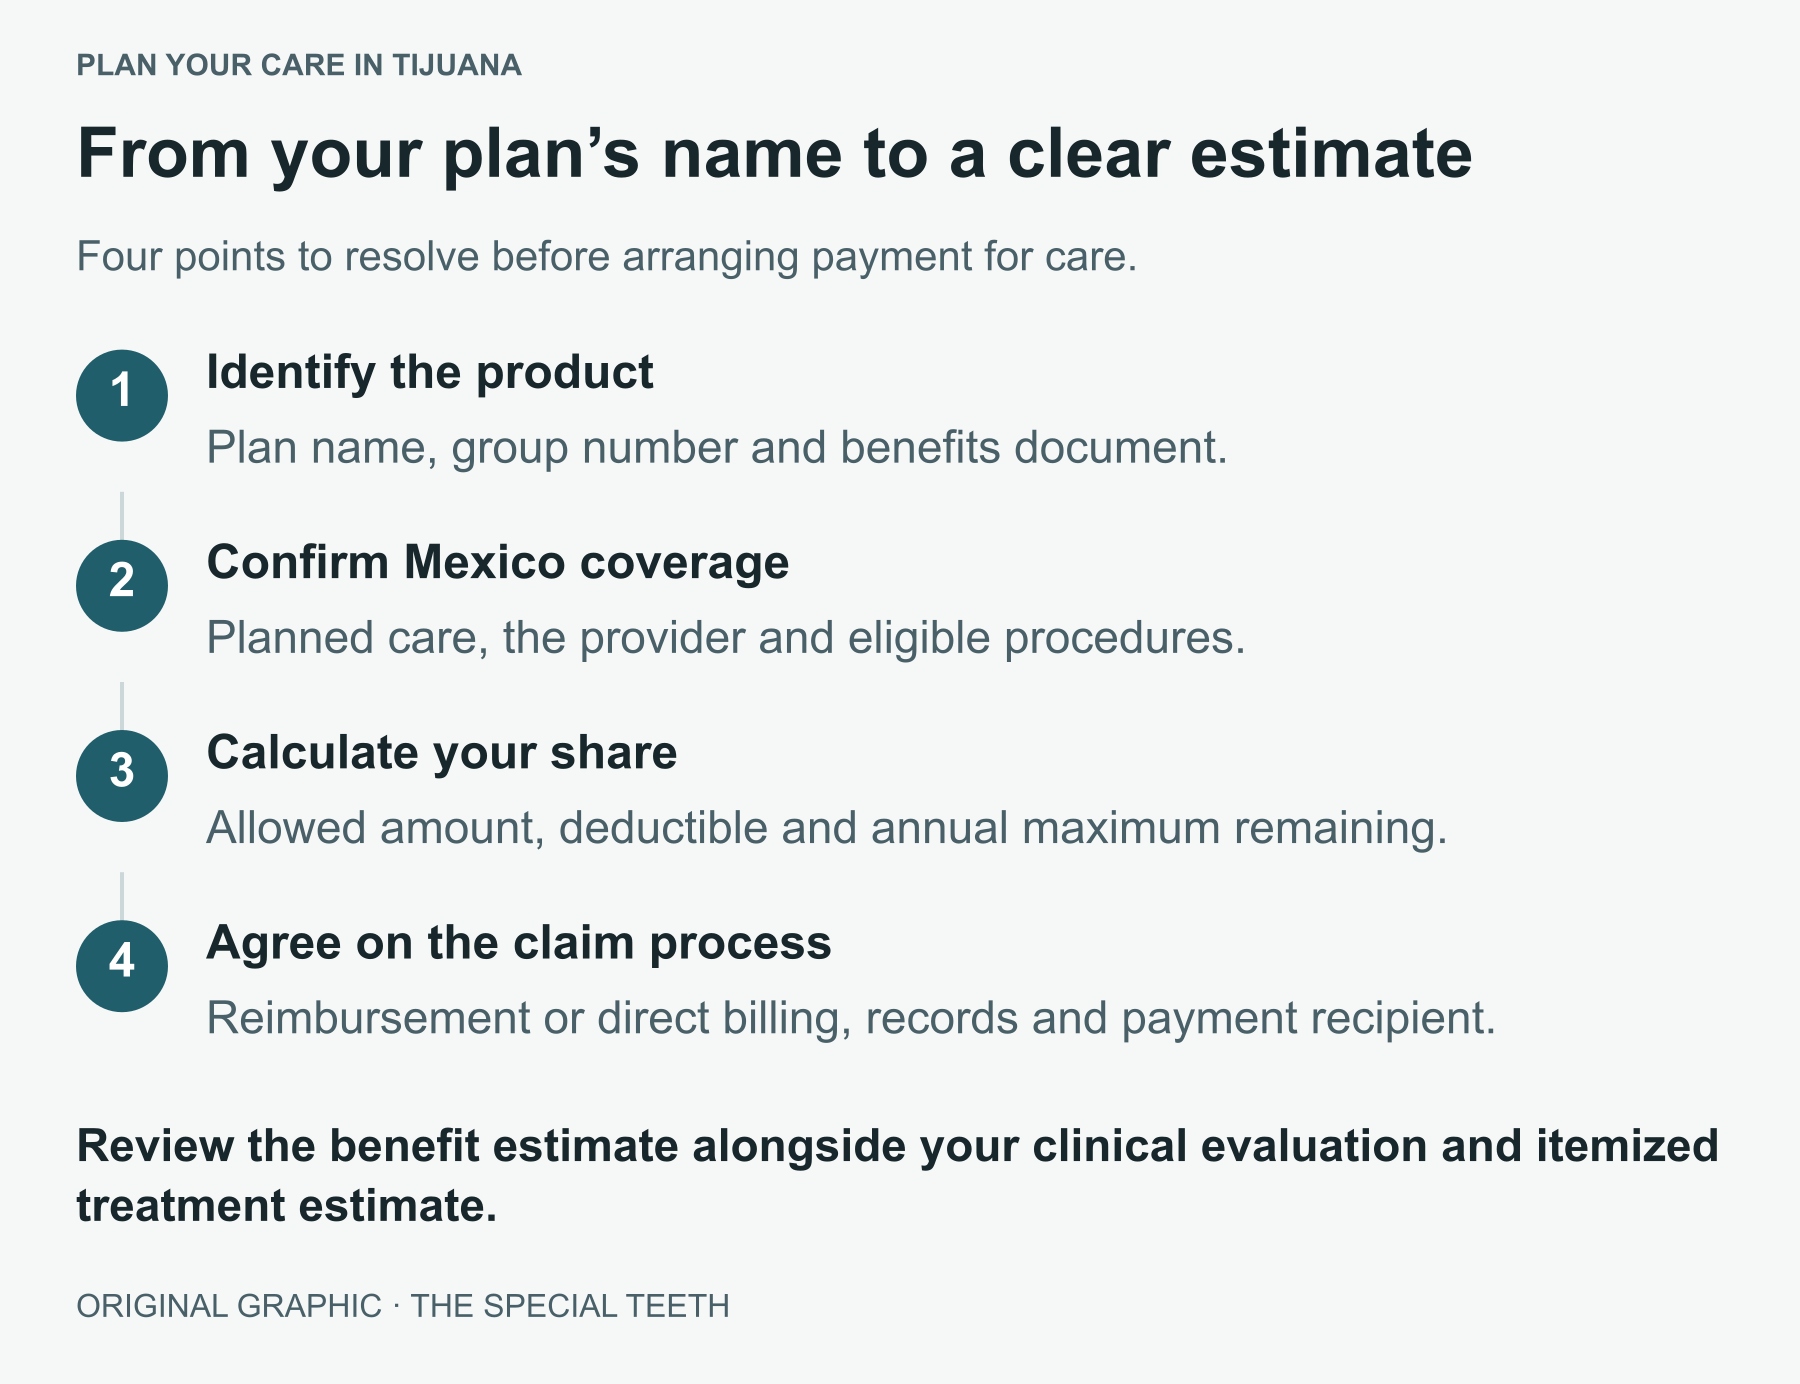
Figure 9 · Editorial graphic
A predetermination estimates benefits using available information. Final payment considers eligibility and the services actually performed.
Related sources
(American Dental Association, 2026a; MetLife, 2025a; Aetna, 2026)
You may encounter two payment routes. With reimbursement, you pay the practice and submit a claim. With direct billing, the practice seeks payment of authorized benefits. Authorization to send payment to the dentist concerns where the money goes and needs to be distinguished from a network participation agreement (American Dental Association, 2026a).
At The Special Teeth, we work with U.S. PPO plans, including Aetna and MetLife. Our team helps you review your coverage and navigate the process that applies to your treatment in Tijuana. Benefits and your share of the cost are confirmed according to your specific plan, procedures, and treatment dates (The Special Teeth, n.d.-a).
Territorial confirmation establishes the possibility of using benefits. The next task is turning percentages into dollar amounts. Continue
08 Deductibles, coinsurance and annual maximums: your share
The allowed amount is the plan’s recognized basis for calculating a service. Outside the network, it can be lower than the dentist’s fee and leave a balance for you to pay. A deductible is the applicable amount you pay before specified benefits begin. Coinsurance divides recognized costs by percentage; a copay sets an amount for a service (Aetna, 2023).
An annual maximum limits what the plan pays during its benefit year under the product’s rules. For example, a US$1,500 maximum caps the insurer’s payment and leaves additional applicable expenses to you. Ask how much remains and which services use that balance. Check your contract for the renewal date.
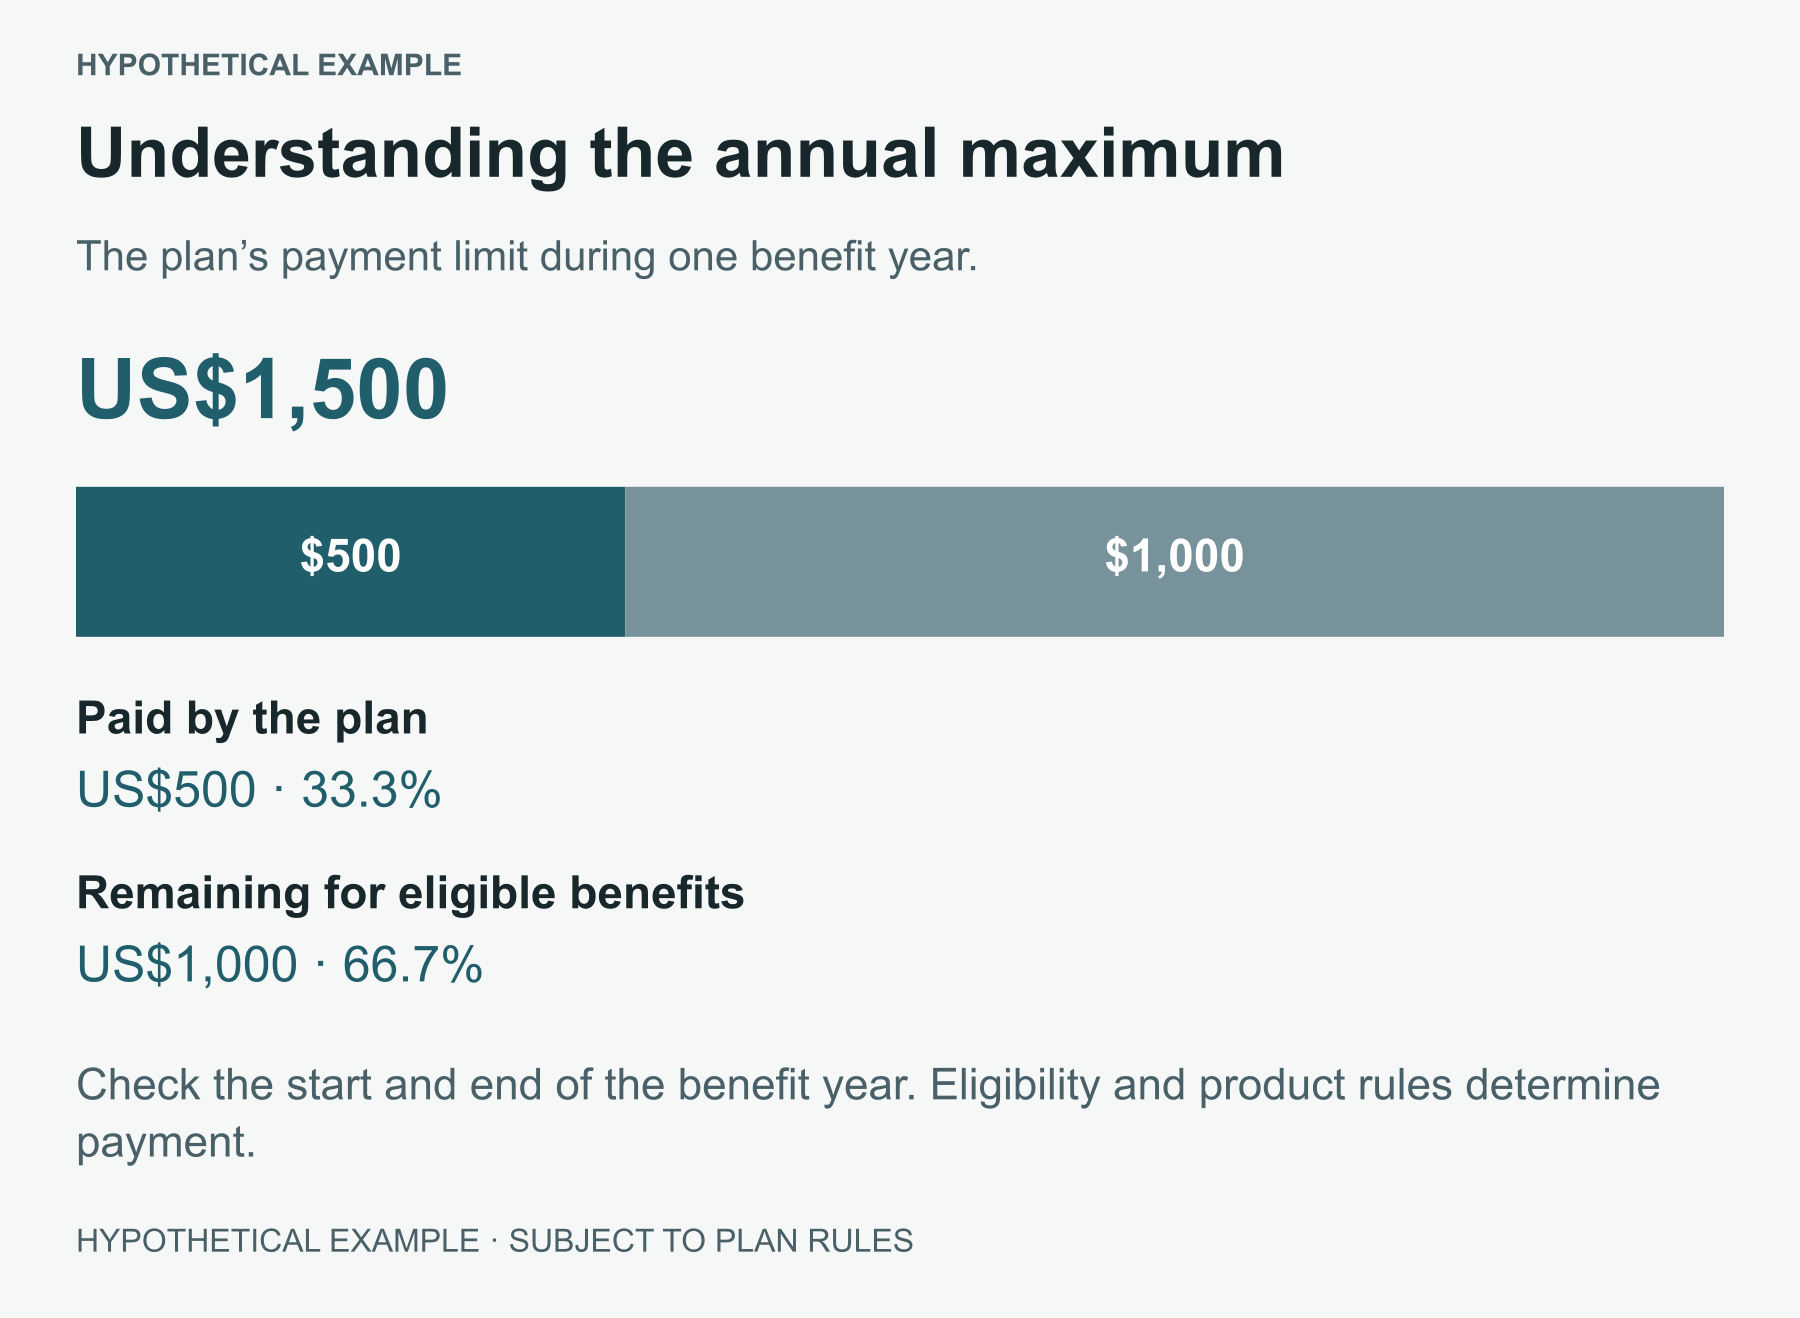
Figure 10 · Editorial graphic
Hypothetical example: a plan has a US$1,500 annual maximum, has paid US$500 and has US$1,000 remaining, subject to eligibility and plan rules.
Related sources
Read the chart data
| Item | Amount |
|---|---|
| Annual maximum | US$1,500 |
| Paid by the plan | US$500 |
| Remaining for eligible benefits | US$1,000 |
For crowns, prostheses and restorations, review replacement intervals. Also ask about a missing-tooth provision, which may affect replacement of a tooth lost before coverage began, and an alternate benefit provision, which can base payment on a less expensive covered option. The clinical choice and benefit calculation can leave a difference in your estimate. (MetLife, 2026b) Whether these provisions are valid depends on the state and plan framework; California’s reform in section 14 is relevant to that review.
A lower price can stretch a remaining annual benefit when the plan calculates payments using those charges. The insurer may also adjust its basis to the local fee. To assess both possibilities, request expected benefits by procedure and keep an estimate of the amount you will pay yourself.
Those provisions become clearer when applied to the care each tooth actually needs. Continue
09 What insurance may cover: root canals, crowns and implants
Plans group services into preventive, basic, major and, where offered, orthodontic benefits. Root canal and periodontal treatment classifications can differ between contracts. Check the actual procedure code against your benefits summary (MetLife, 2025d).
| Care | Purpose | Factors affecting payment |
|---|---|---|
| Examination and imaging | Diagnose and monitor oral health | Frequency, imaging type and benefits already used |
| Cleaning and prevention | Maintain health according to assessment | Age, interval and indicated type of cleaning |
| Fillings and extractions | Restore or address an affected tooth | Surfaces, material and complexity |
| Root canal treatment | Treat the tooth’s interior to preserve it | Tooth, plan category and subsequent restoration |
| Periodontal care | Treat gums and supporting tissues | Diagnosis, quadrants, records and maintenance |
| Crowns and prostheses | Restore protection or function | Clinical need, material, replacement and alternate benefits |
| Implants and rehabilitation | Replace teeth with prosthetic components | Stage-specific benefits, exclusions and limits |
| Orthodontics and aligners | Correct tooth position and bite | Age, lifetime maximum and payment schedule |
For a root canal, request the fee for the endodontic procedure and for the indicated final restoration. For implants, separate surgery, the abutment, the crown and additional procedures. That breakdown helps establish which part the policy recognizes and which part belongs in your own budget (Kennedy, 2026).
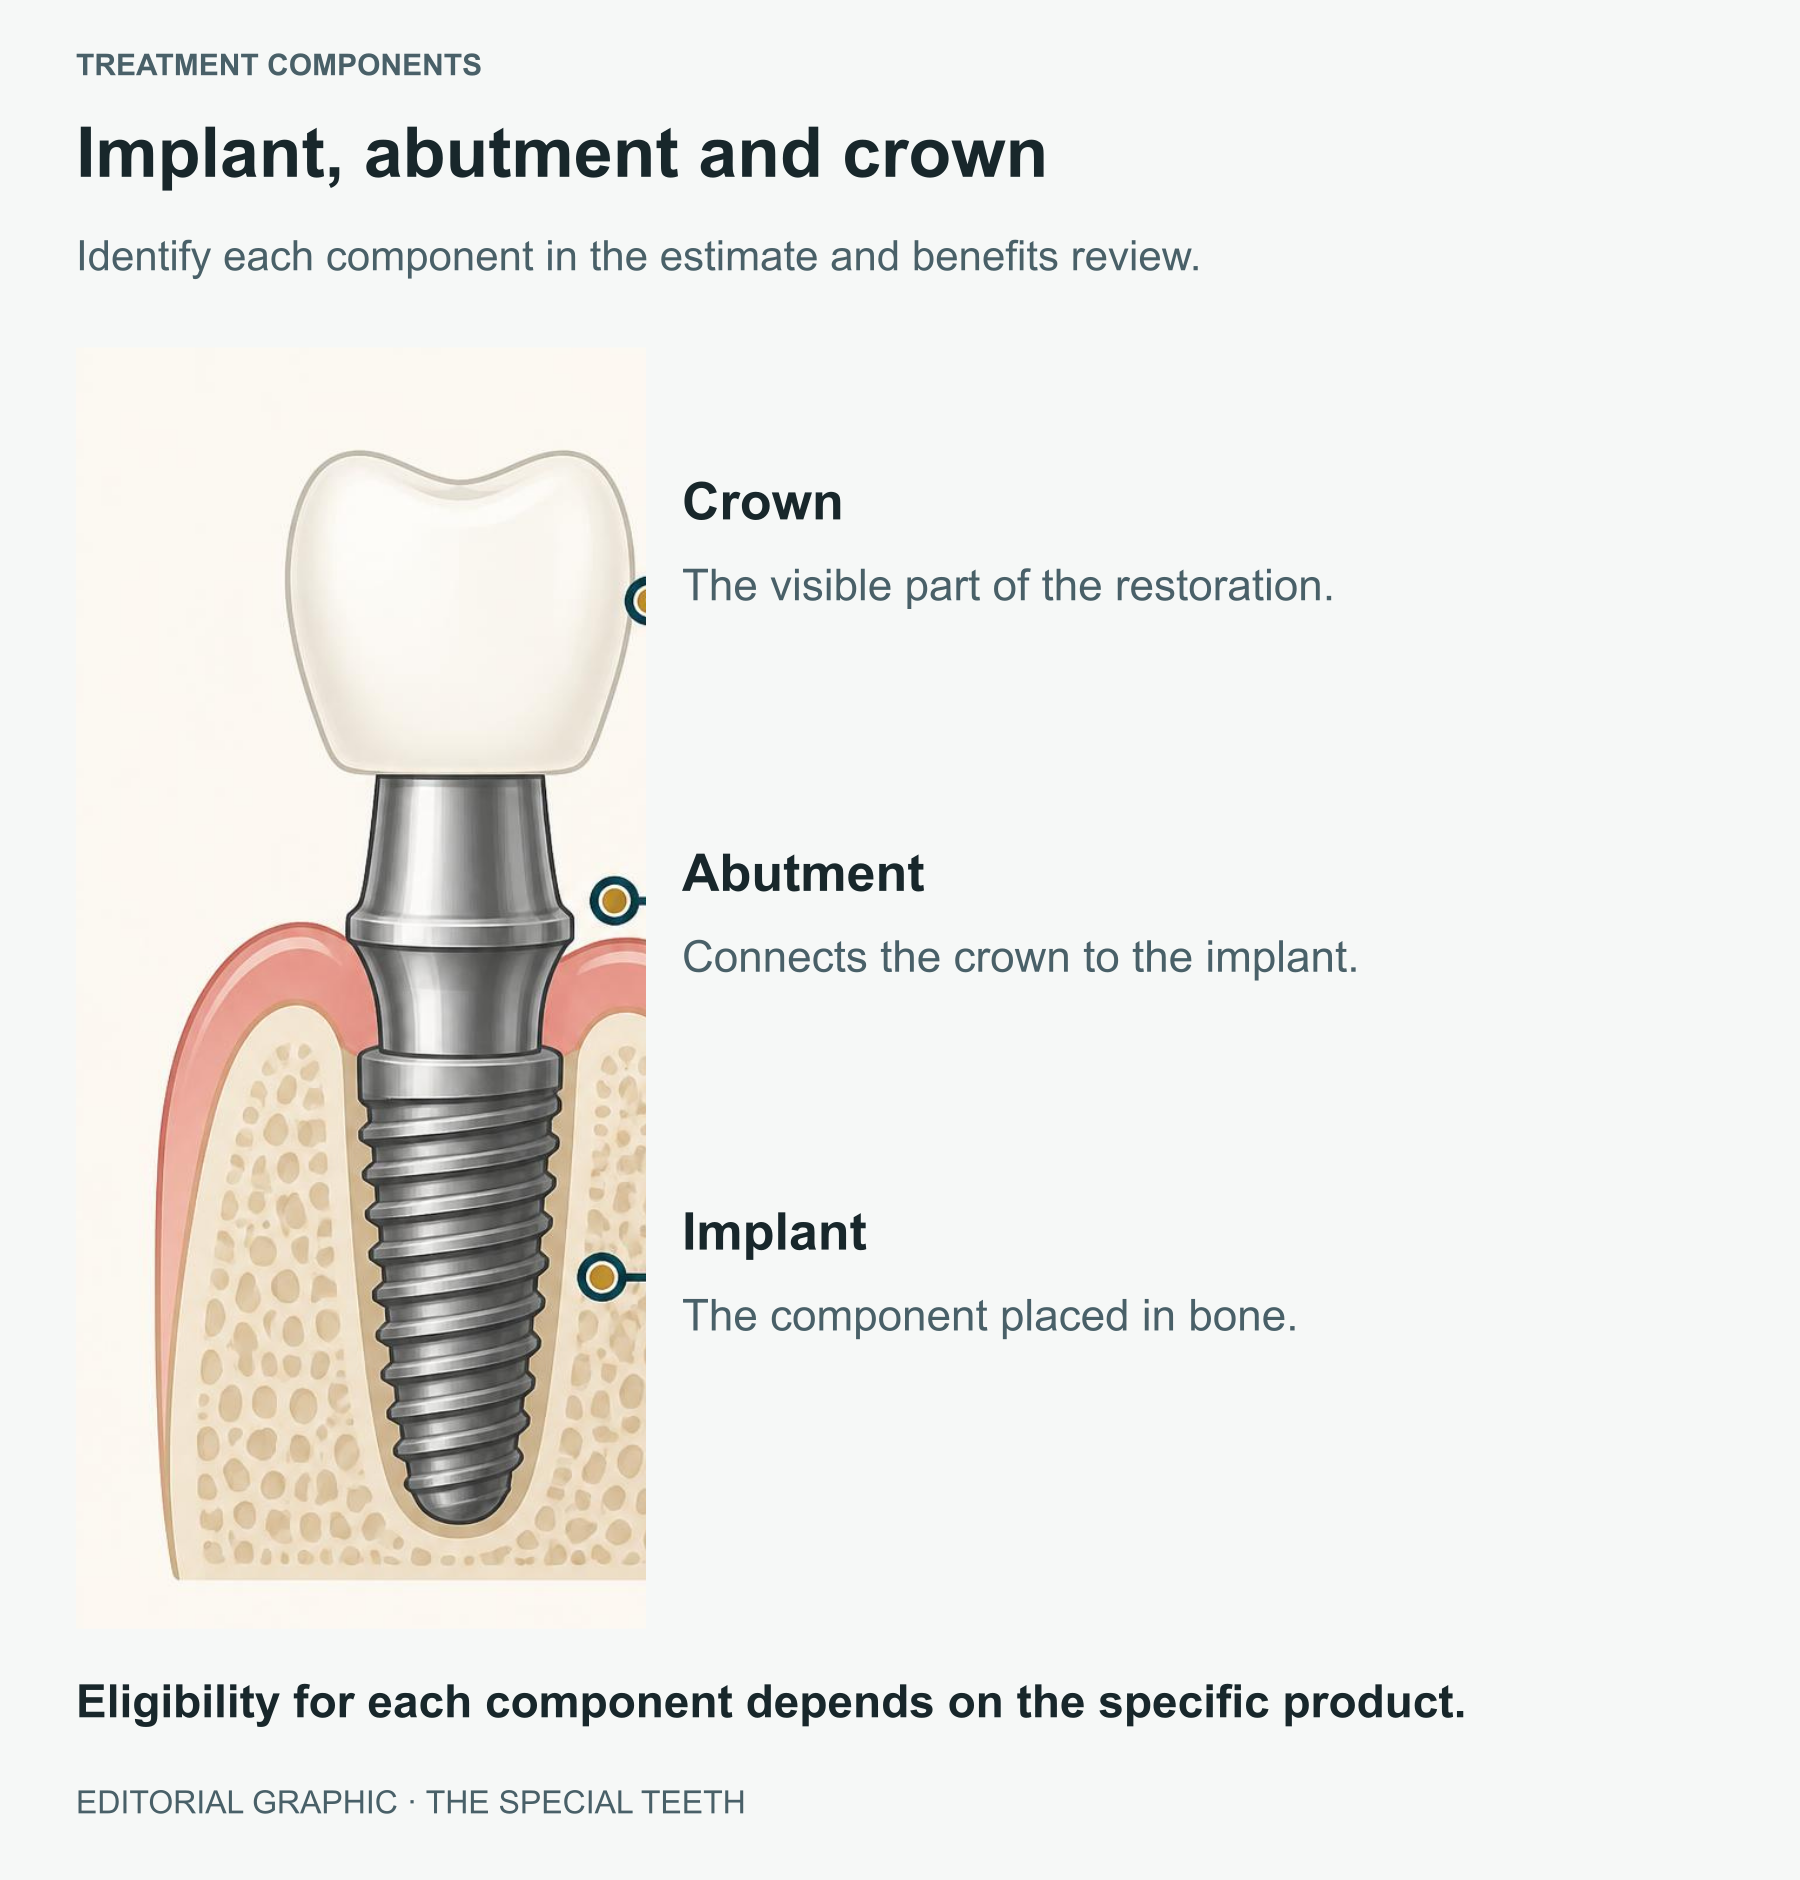
Figure 11 · Editorial graphic
AI-generated conceptual illustration. Implant, abutment and crown are components to identify in the estimate and check separately with the plan.
Related sources
All-on-4 or All-on-6 rehabilitation combines procedures and components that need individual review. An annual maximum of US$1,500 or US$2,000 would fund only a portion of a more expensive treatment if its services are eligible. Itemization avoids treating a commercial treatment name as a single insured benefit.
Services performed solely for cosmetic reasons are commonly excluded. For crowns or veneers, the clinical reason and documentation affect the review. For orthodontics, confirm whether benefits are paid over the course of treatment and what happens if coverage changes before completion (MetLife, 2025d; MetLife, 2026b).
Figure 12 · Stock photograph
Dental study model. Photograph by Kaboompics / Karola G on Pexels; stock image illustrating work with models.
Kaboompics / Karola G · Photograph source
After identifying eligible treatment, you can calculate savings using the complete cost of care. Continue
10 Your costs in Tijuana after insurance and travel
Your cost is the full treatment price minus expected plan payments, plus transport, accommodation, fees and follow-up. Compare that result across two clinically equivalent proposals when deciding where to receive care.
The following example is hypothetical. It assumes an equivalent crown quoted at US$1,200 in the United States and US$450 in Tijuana, both fees fully recognized, a remaining US$50 deductible and a plan paying 50% afterward. It assumes Mexican care is covered, sufficient annual benefits remain and the Tijuana trip adds US$100 in expenses.
| Illustrative item | United States | Tijuana |
|---|---|---|
| Recognized fee | US$1,200 | US$450 |
| Remaining deductible | US$50 | US$50 |
| Plan payment | US$575 | US$200 |
| Patient payment for the crown | US$625 | US$250 |
| Assumed travel and additional expenses | US$0 | US$100 |
| Total patient cost | US$625 | US$350 |
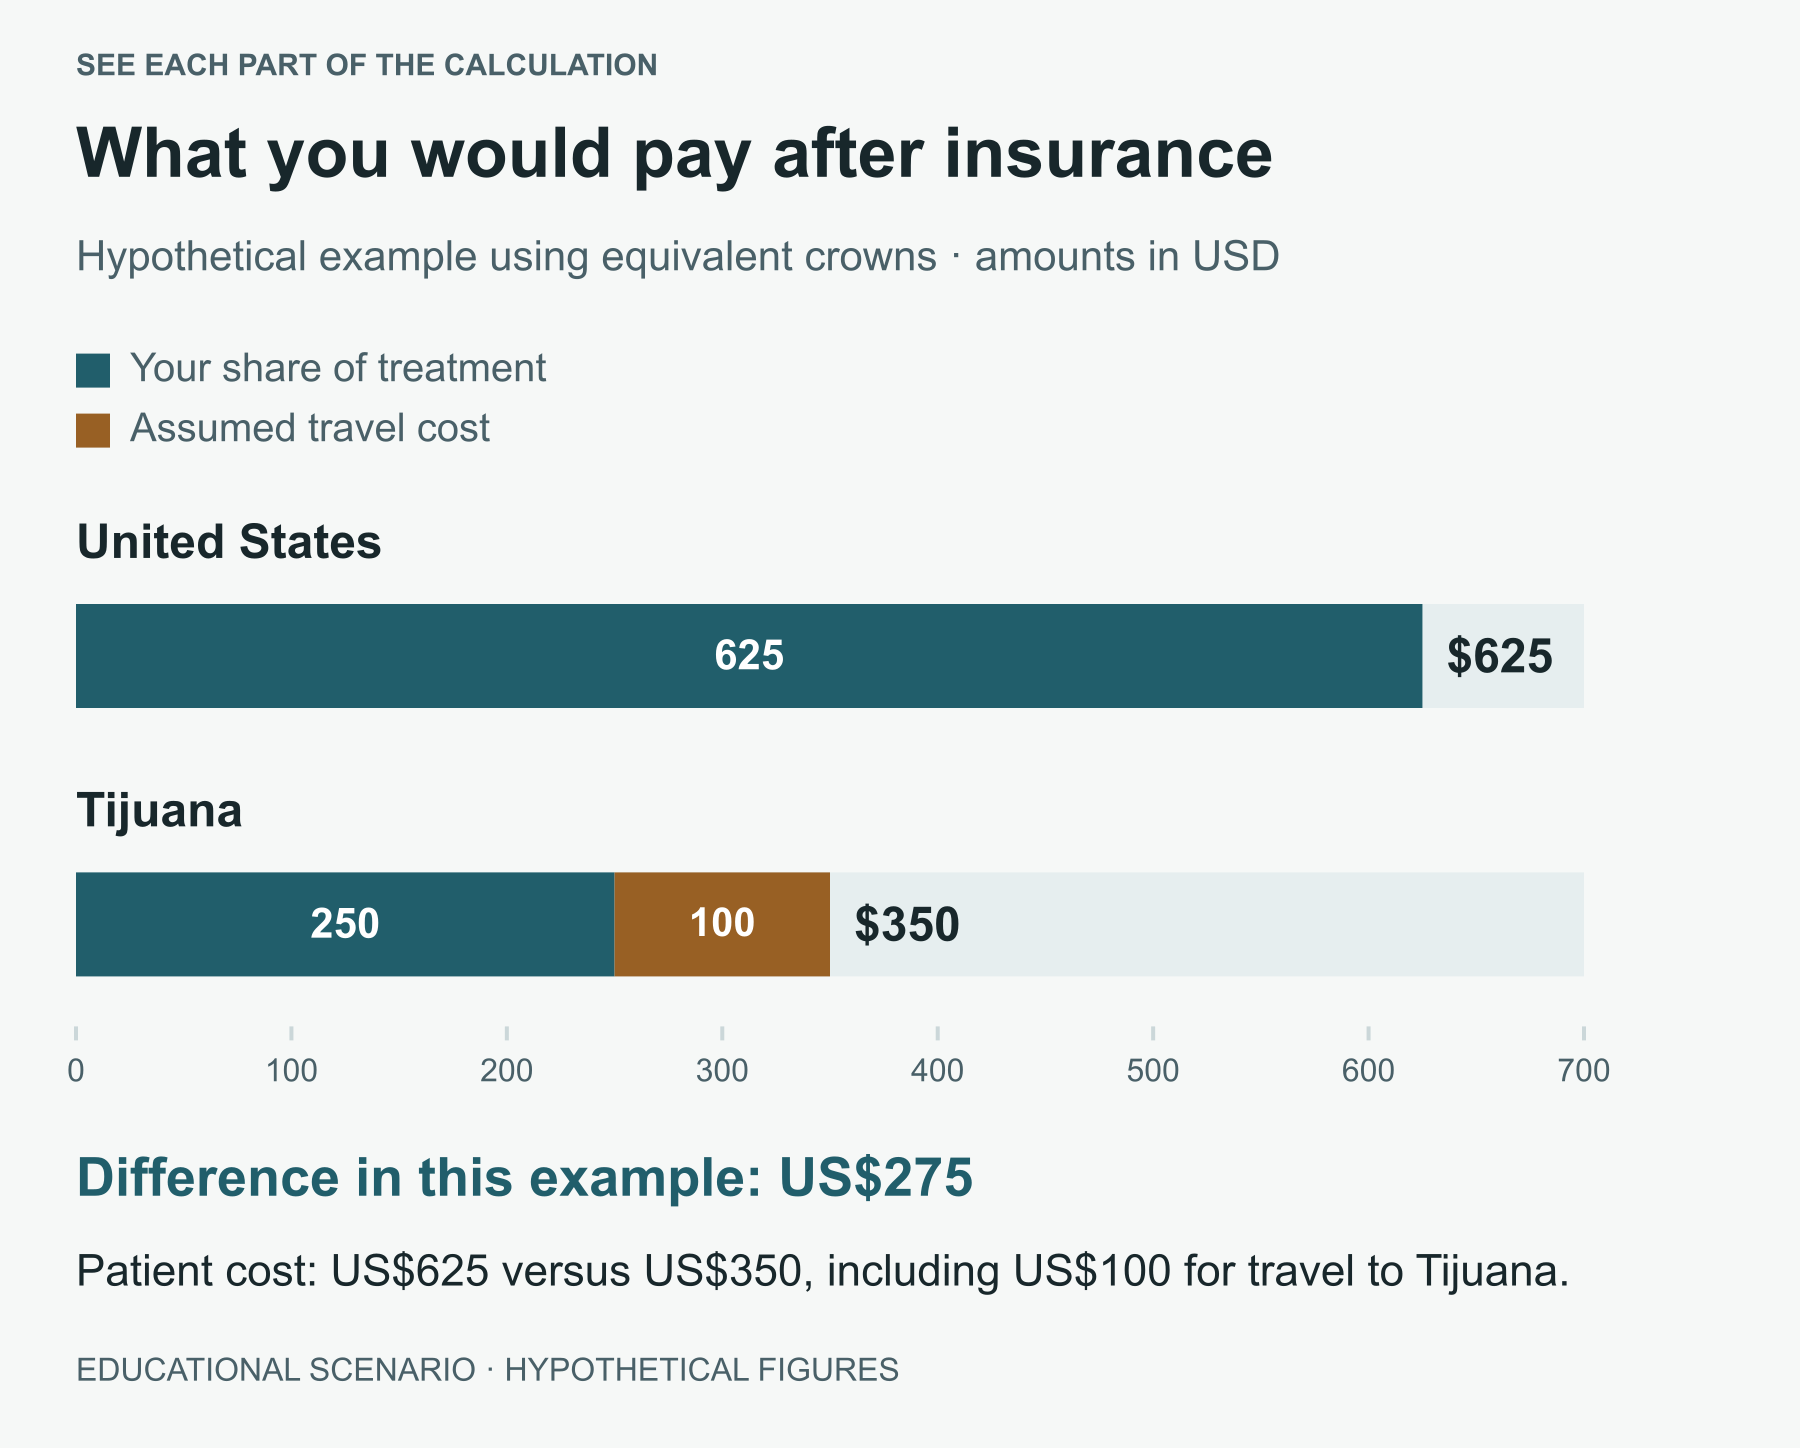
Figure 13 · Editorial graphic
Assumes allowed charges of US$1,200 and US$450, a US$50 remaining deductible for each alternative, a 50% plan payment after that deductible and sufficient annual benefits. Mexico coverage is assumed. A new premium is excluded here and discussed separately in the article.
Read the chart data
| Example component | United States | Tijuana |
|---|---|---|
| Allowed charge | US$1,200 | US$450 |
| Remaining deductible | US$50 | US$50 |
| Plan payment | US$575 | US$200 |
| Your share of treatment | US$625 | US$250 |
| Assumed travel cost | US$0 | US$100 |
| Total patient cost | US$625 | US$350 |
The difference would be US$275. If the plan recognized only US$300 of Tijuana’s US$450 fee, it would pay US$125 after the deductible. Your total would be US$425, including the US$100 trip. If it recognized the full fee but only US$100 remained in annual benefits, payment would be capped at that balance and your total would be US$450.
Premiums also matter when deciding whether to enroll. In a separate scenario, a new policy costing US$30 per month for 12 months would cost US$360. Adding that to the first example’s US$350 patient cost produces US$710 for that year and crown. Paying US$450 directly plus US$100 travel would total US$550. The policy’s value would then also depend on benefits used during the rest of the year.
For someone already covered, the trip may combine existing benefits with an accessible local fee. For someone shopping for coverage, comparing premiums, waiting periods and international provisions helps identify whether a product will contribute enough toward the planned treatment.
An estimated payment becomes a collected benefit through a complete clinical record and claim. Continue
11 Dental reimbursement in Mexico and direct billing: the records
Before care, agree who will submit the pretreatment estimate and who will file the final claim. Keep the benefit summary, insurer’s response and itemized treatment proposal. For direct billing, request written terms for deposits, estimated payments and adjustments after the plan makes its decision.
MetLife describes claim information including member and provider identification, dates, procedures and receipts. Depending on treatment, it may require CDT codes, tooth or surface details, X-rays and clinical information. CDT is the US coding system used to describe dental procedures. Ask the insurer which format and documentation it accepts from a clinician in Mexico (MetLife, 2025a).
Currency needs its own review. Aetna FEDVIP 2026 pays international claims in US dollars and uses the exchange rate in effect when the claim is processed. Your bank card may use a different date or add a foreign transaction fee. Retain the original-currency receipt and the corresponding card charge (Aetna, 2026).
When the explanation of benefits, or EOB, arrives, compare it with the invoice. Check the processed procedure, allowed amount, applied deductible and issued payment. Also confirm whether the money went to you or the practice as agreed. Reconciling those records helps identify outstanding documents or differences that need clarification.
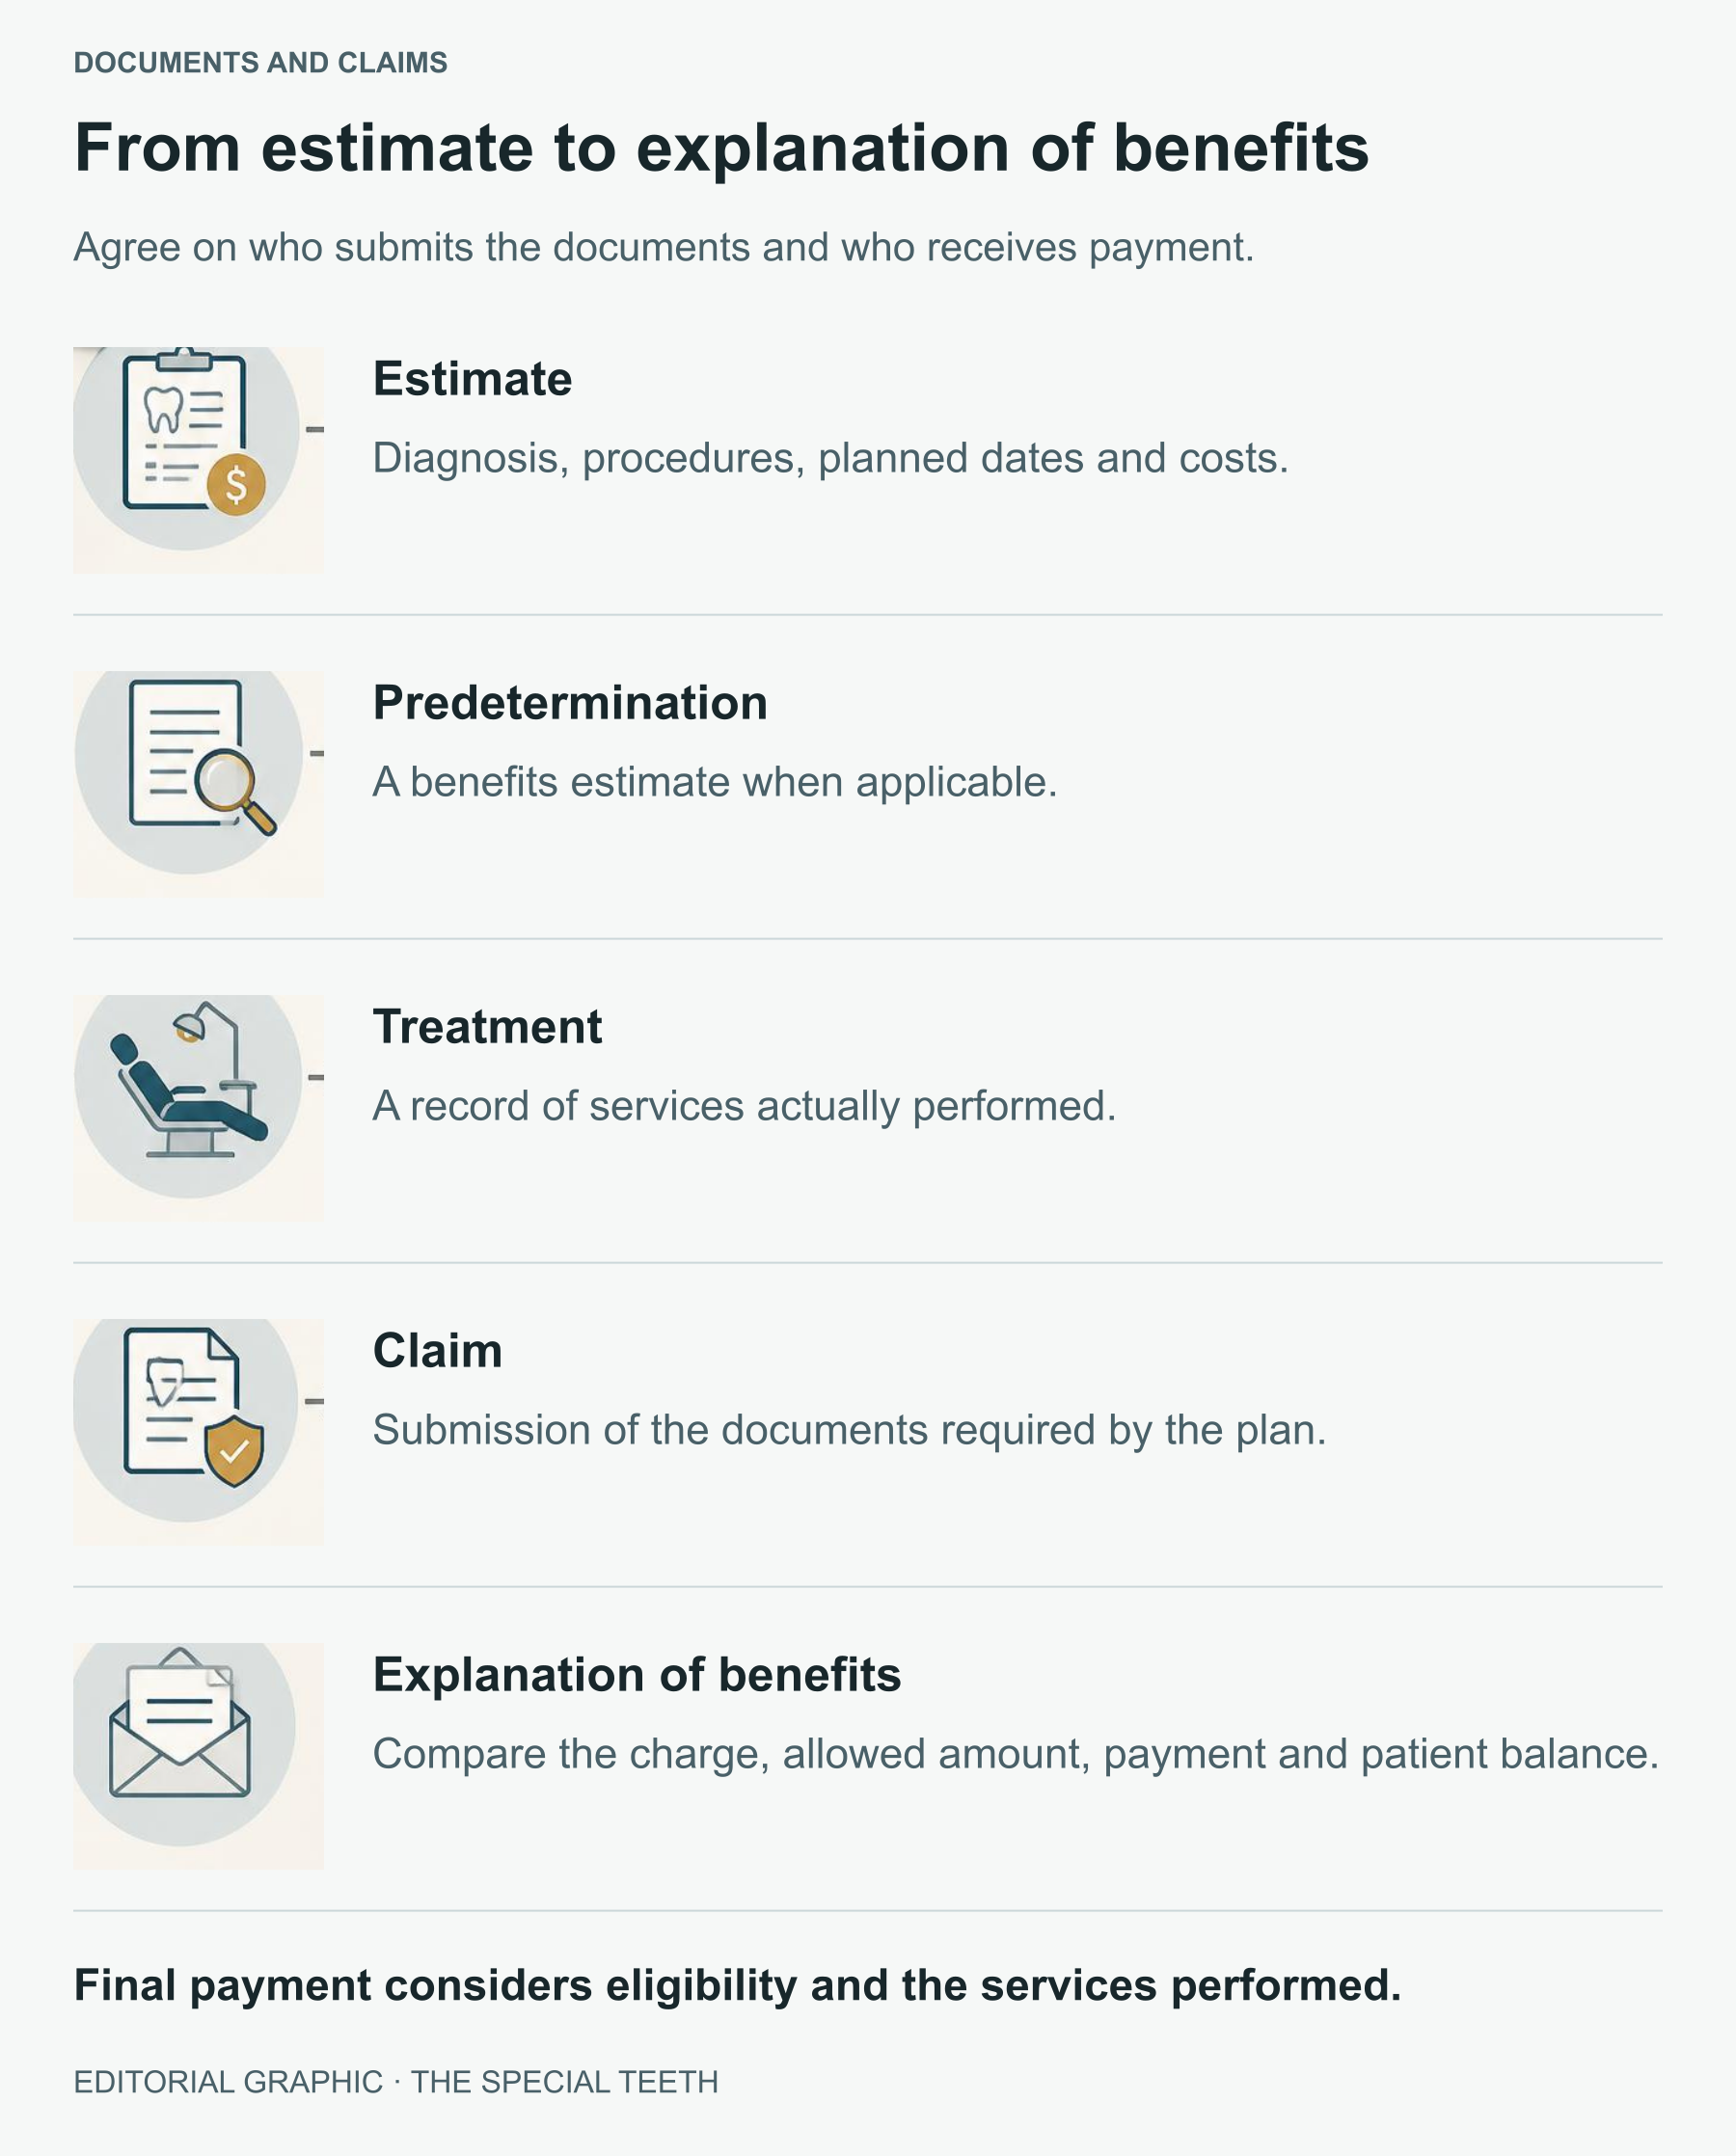
Figure 14 · Editorial graphic
The explanation of benefits helps reconcile procedures, allowed amounts and payments with the bill.
Related sources
That same record helps when a second plan is involved or a payment decision needs review. Continue
12 Two plans and one bill: understanding a denial
If you have coverage through your employer and your partner’s employer, disclose both before treatment. Coordination of benefits determines which pays first and how the second plan contributes. Reducing the remaining bill depends on coordination rules and each plan recognizing care in Mexico. Two cards mean calculating two contracts against one invoice (American Dental Association, n.d.-a).
For a denial, identify the written reason: territorial exclusion, waiting period, missing documentation, frequency limit, exhausted maximum or a dental necessity determination. An administrative error may need corrected information; a clinical review may need X-rays and a clinician’s report. MetLife’s FEDVIP 2026 brochure describes a reconsideration process with its own requirements and deadlines (MetLife, 2026b).
Request your product’s review process and filing deadline, retain copies and record submission. For an employment benefit, consult the program administrator as well. While a review is pending, confirm the practice balance and agreed payment dates. This keeps the claim moving while preserving a clear understanding of the treatment’s financial arrangements.
Choosing with confidence also means understanding who oversees the product, the clinician and the practice. Continue
13 FDA, COFEPRIS and checking your dentist’s credentials
Regulation helps you assess the product being used, the professional recommending it and the conditions of the practice. A dental trip also involves the contract funding care. Identifying each responsibility helps you request the appropriate evidence.
FDA and devices for the US market
The Food and Drug Administration, FDA, oversees medical devices intended for the US market, including dental products. Its October 2024 final guidance sets performance criteria for endosseous implants and abutments within a 510(k) review pathway. That pathway concerns substantial equivalence and should be identified using its appropriate regulatory terminology (FDA, 2024).
If a practice refers to an FDA authorization, ask for the device’s manufacturer, model and verifiable reference. That information concerns the product. Professional licensing and the practice’s sanitary requirements belong to their competent authorities. In California, the Dental Board of California licenses and regulates dentists and dental assistants within its jurisdiction (State of California, 2025).
COFEPRIS and sanitary oversight in Mexico
Mexico’s Federal Commission for Protection Against Sanitary Risks, COFEPRIS, publishes information on medical device registration and good manufacturing practices. For a device used in Mexico, ask for identification and the registration or authorization applicable under the Mexican framework. That allows the material or system to be documented in your records (COFEPRIS, 2025).
In Baja California, COEPRIS BC conducts sanitary oversight of establishments. Its 2025 information describes operating notices, licenses where applicable and professional documentation. It also explains that REPSSABI is a voluntary provider register available to the public, with listed establishments remaining subject to inspection (COEPRIS BC, 2025).
Professional qualifications have a separate verification route. In 2025, Mexico’s Secretariat of Public Education, SEP, introduced the National Registry of Professionals portal for checking professional credentials. Request your dentist’s full name and cédula profesional, plus supporting qualifications for an advertised specialty. The registry helps verify the professional who will perform your procedure (Secretaría de Educación Pública, 2025).
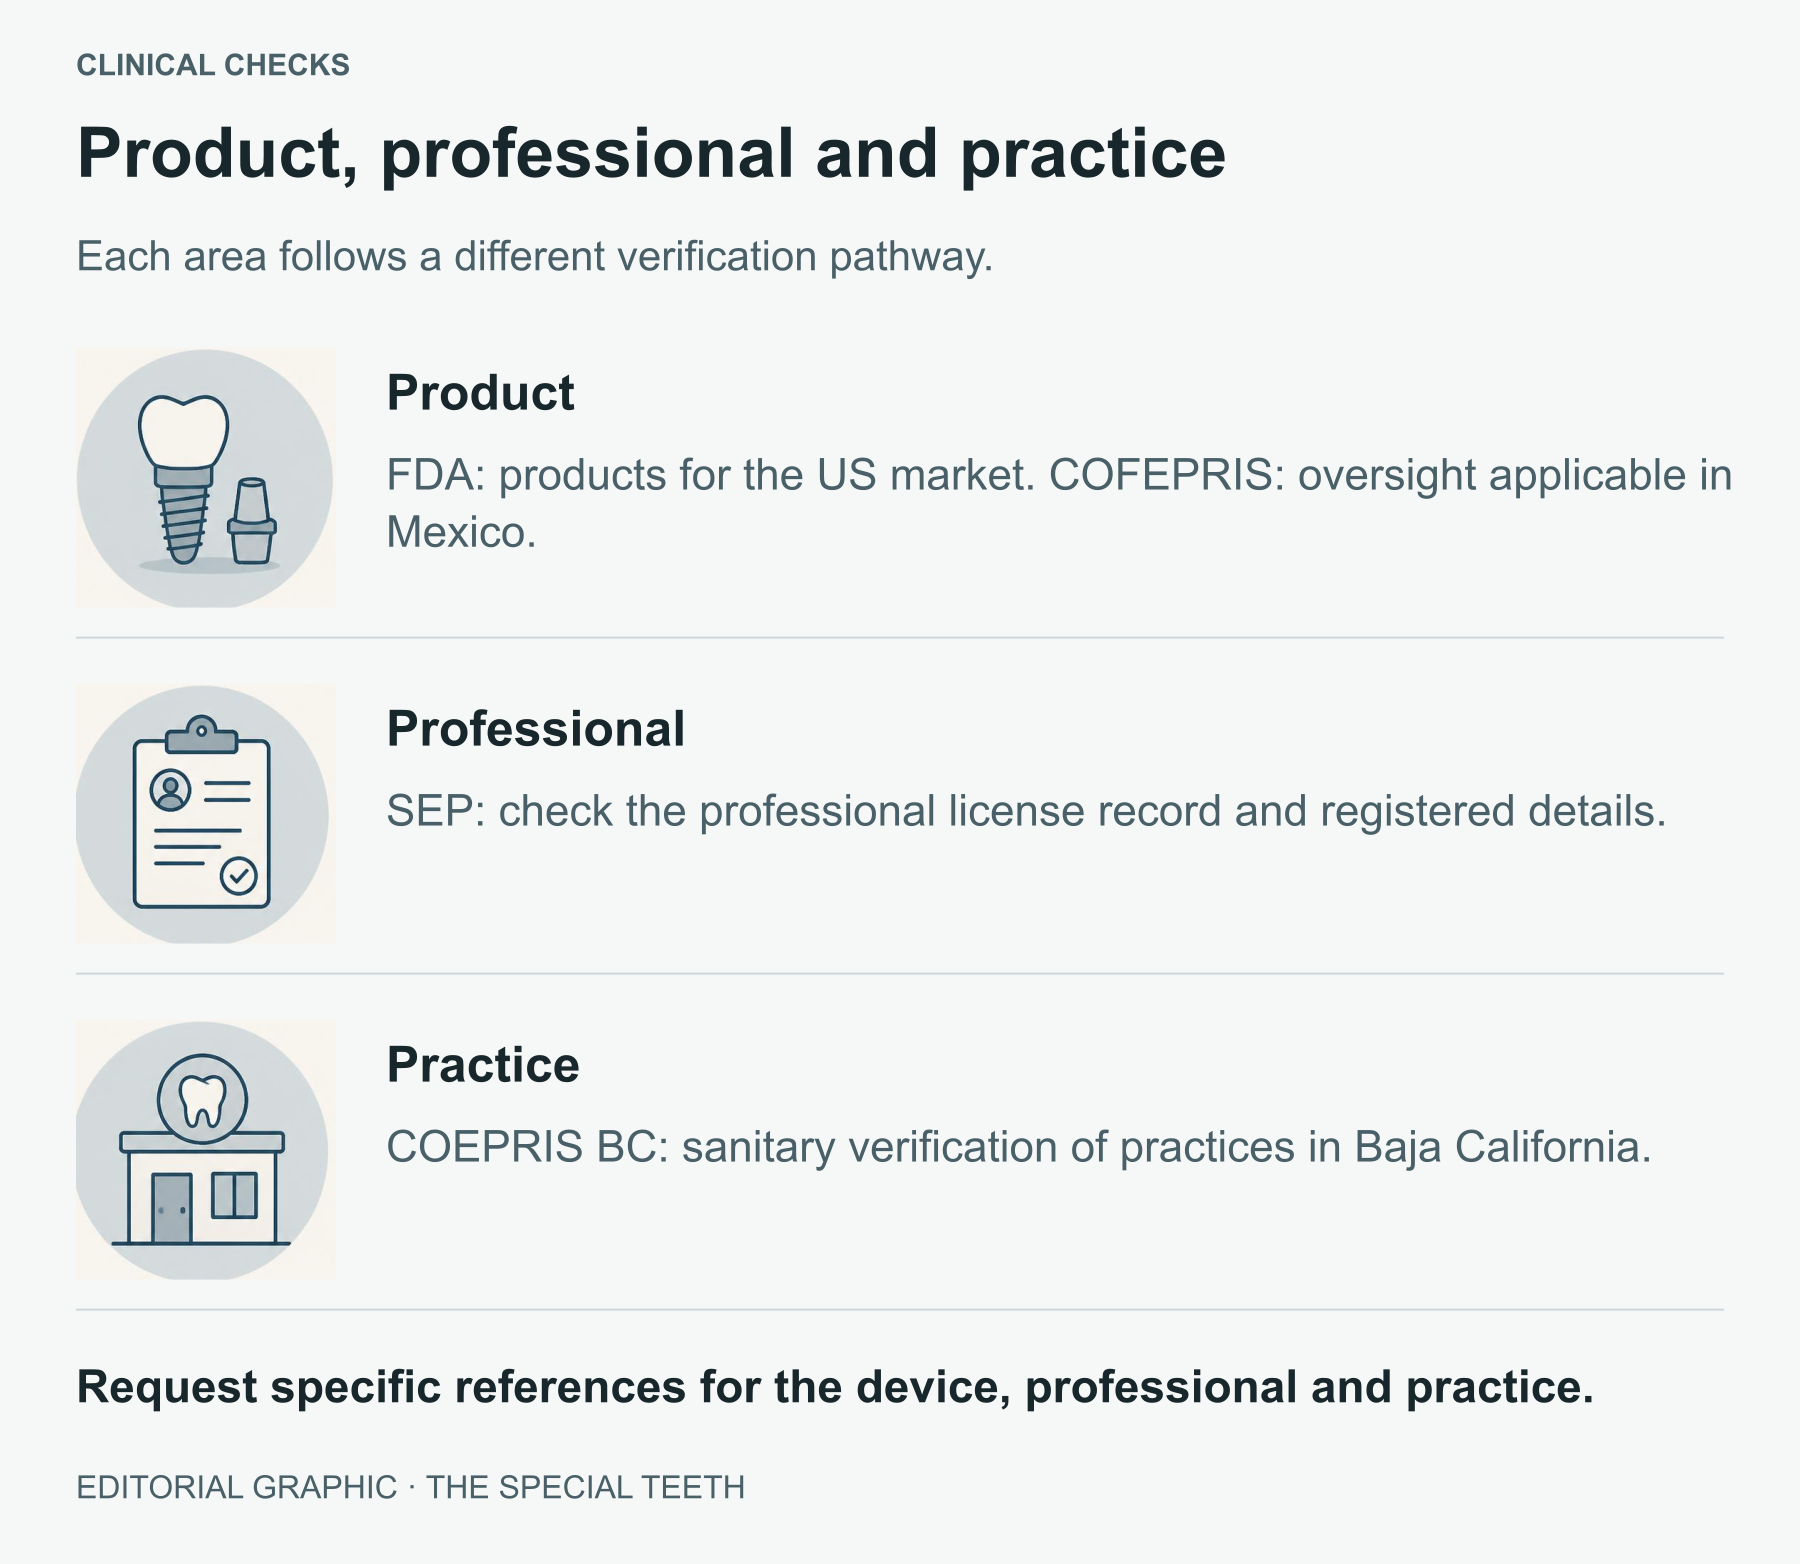
Figure 15 · Editorial graphic
Product, professional-credential and practice checks follow different authorities. FDA concerns products for the US market; the oversight applicable in Mexico should be checked with Mexican authorities.
Related sources
(FDA, 2024; COFEPRIS, 2025; COEPRIS BC, 2025; Secretaría de Educación Pública, 2025)
After identifying the product, clinician and establishment, you can locate the authority responsible for your financial benefit. Continue
14 Who regulates dental insurance in the United States
The authority depends on coverage type and funding. US insurers are subject to state oversight, while workplace programs may add federal obligations. In California, responsibilities are divided between the Department of Managed Health Care, DMHC, and the Department of Insurance, CDI, according to the entity and product. AB 952 describes that division for dental coverage (A.B. 952, 2023).
If your employer self-funds benefits, the brand on your card may be the administrator. Private-sector plans subject to the Employee Retirement Income Security Act (ERISA) involve the Department of Labor’s Employee Benefits Security Administration, EBSA. Its enforcement manual, updated in July 2026, addresses plan information, fiduciary duties and benefit claims procedures. Public-sector and church programs may follow other frameworks (U.S. Department of Labor, 2026; U.S. Department of Labor, n.d.).
Request the Summary Plan Description or evidence of coverage and ask whether the arrangement is fully insured or self-funded. From January 2025, AB 952 requires disclosure of State Regulated status through provider portals or on request. It also requires that wording on identification cards for applicable California-regulated coverage within the law’s scope (A.B. 952, 2023).
Specific changes for California patients
In January 2025, CDI explained AB 1048 requirements: it prohibits dental waiting periods in large-group policies and preexisting-condition provisions in dental policies covered by the law, for policies issued or renewed from January 2025. That distinction matters when reviewing a tooth lost before enrollment or a waiting period imposed by the plan (California Department of Insurance, 2025).
Applicability needs confirmation for your product’s legal framework; a self-funded workplace program may follow different rules. These protections also leave a separate territorial question to answer. For care in Tijuana, confirm that your contract permits the procedures in Mexico.
For a DMHC-regulated plan, the department’s process directs members to complain to the plan first and then seek departmental assistance under its requirements. For a CDI-regulated policy or an ERISA workplace benefit, use the corresponding route. In FEDVIP, consult the claims and review process in your specific brochure (California Department of Managed Health Care, n.d.).
Clinical care in Tijuana also involves the Mexican framework. Knowing which issue belongs on each side of the border makes follow-up more effective. Continue
15 Patient rights and complaints in Mexico
Mexico’s National Insurance and Bonding Commission, CNSF, supervises insurers’ operation, solvency and financial stability. The National Commission for the Protection and Defense of Financial Services Users, CONDUSEF, provides guidance and complaint mechanisms involving financial institutions within its jurisdiction. CNSF itself distinguishes contractual complaints from its administrative oversight functions (CNSF, n.d.; CNSF, 2025).
For a US policy, start with the issuer, administrator and regulator named in the documents. Visiting a Mexican dentist leaves the benefit claim subject to the route applicable to the original contract. A Mexican-issued policy requires its own review of the authorized entity, policy terms and complaint channels.
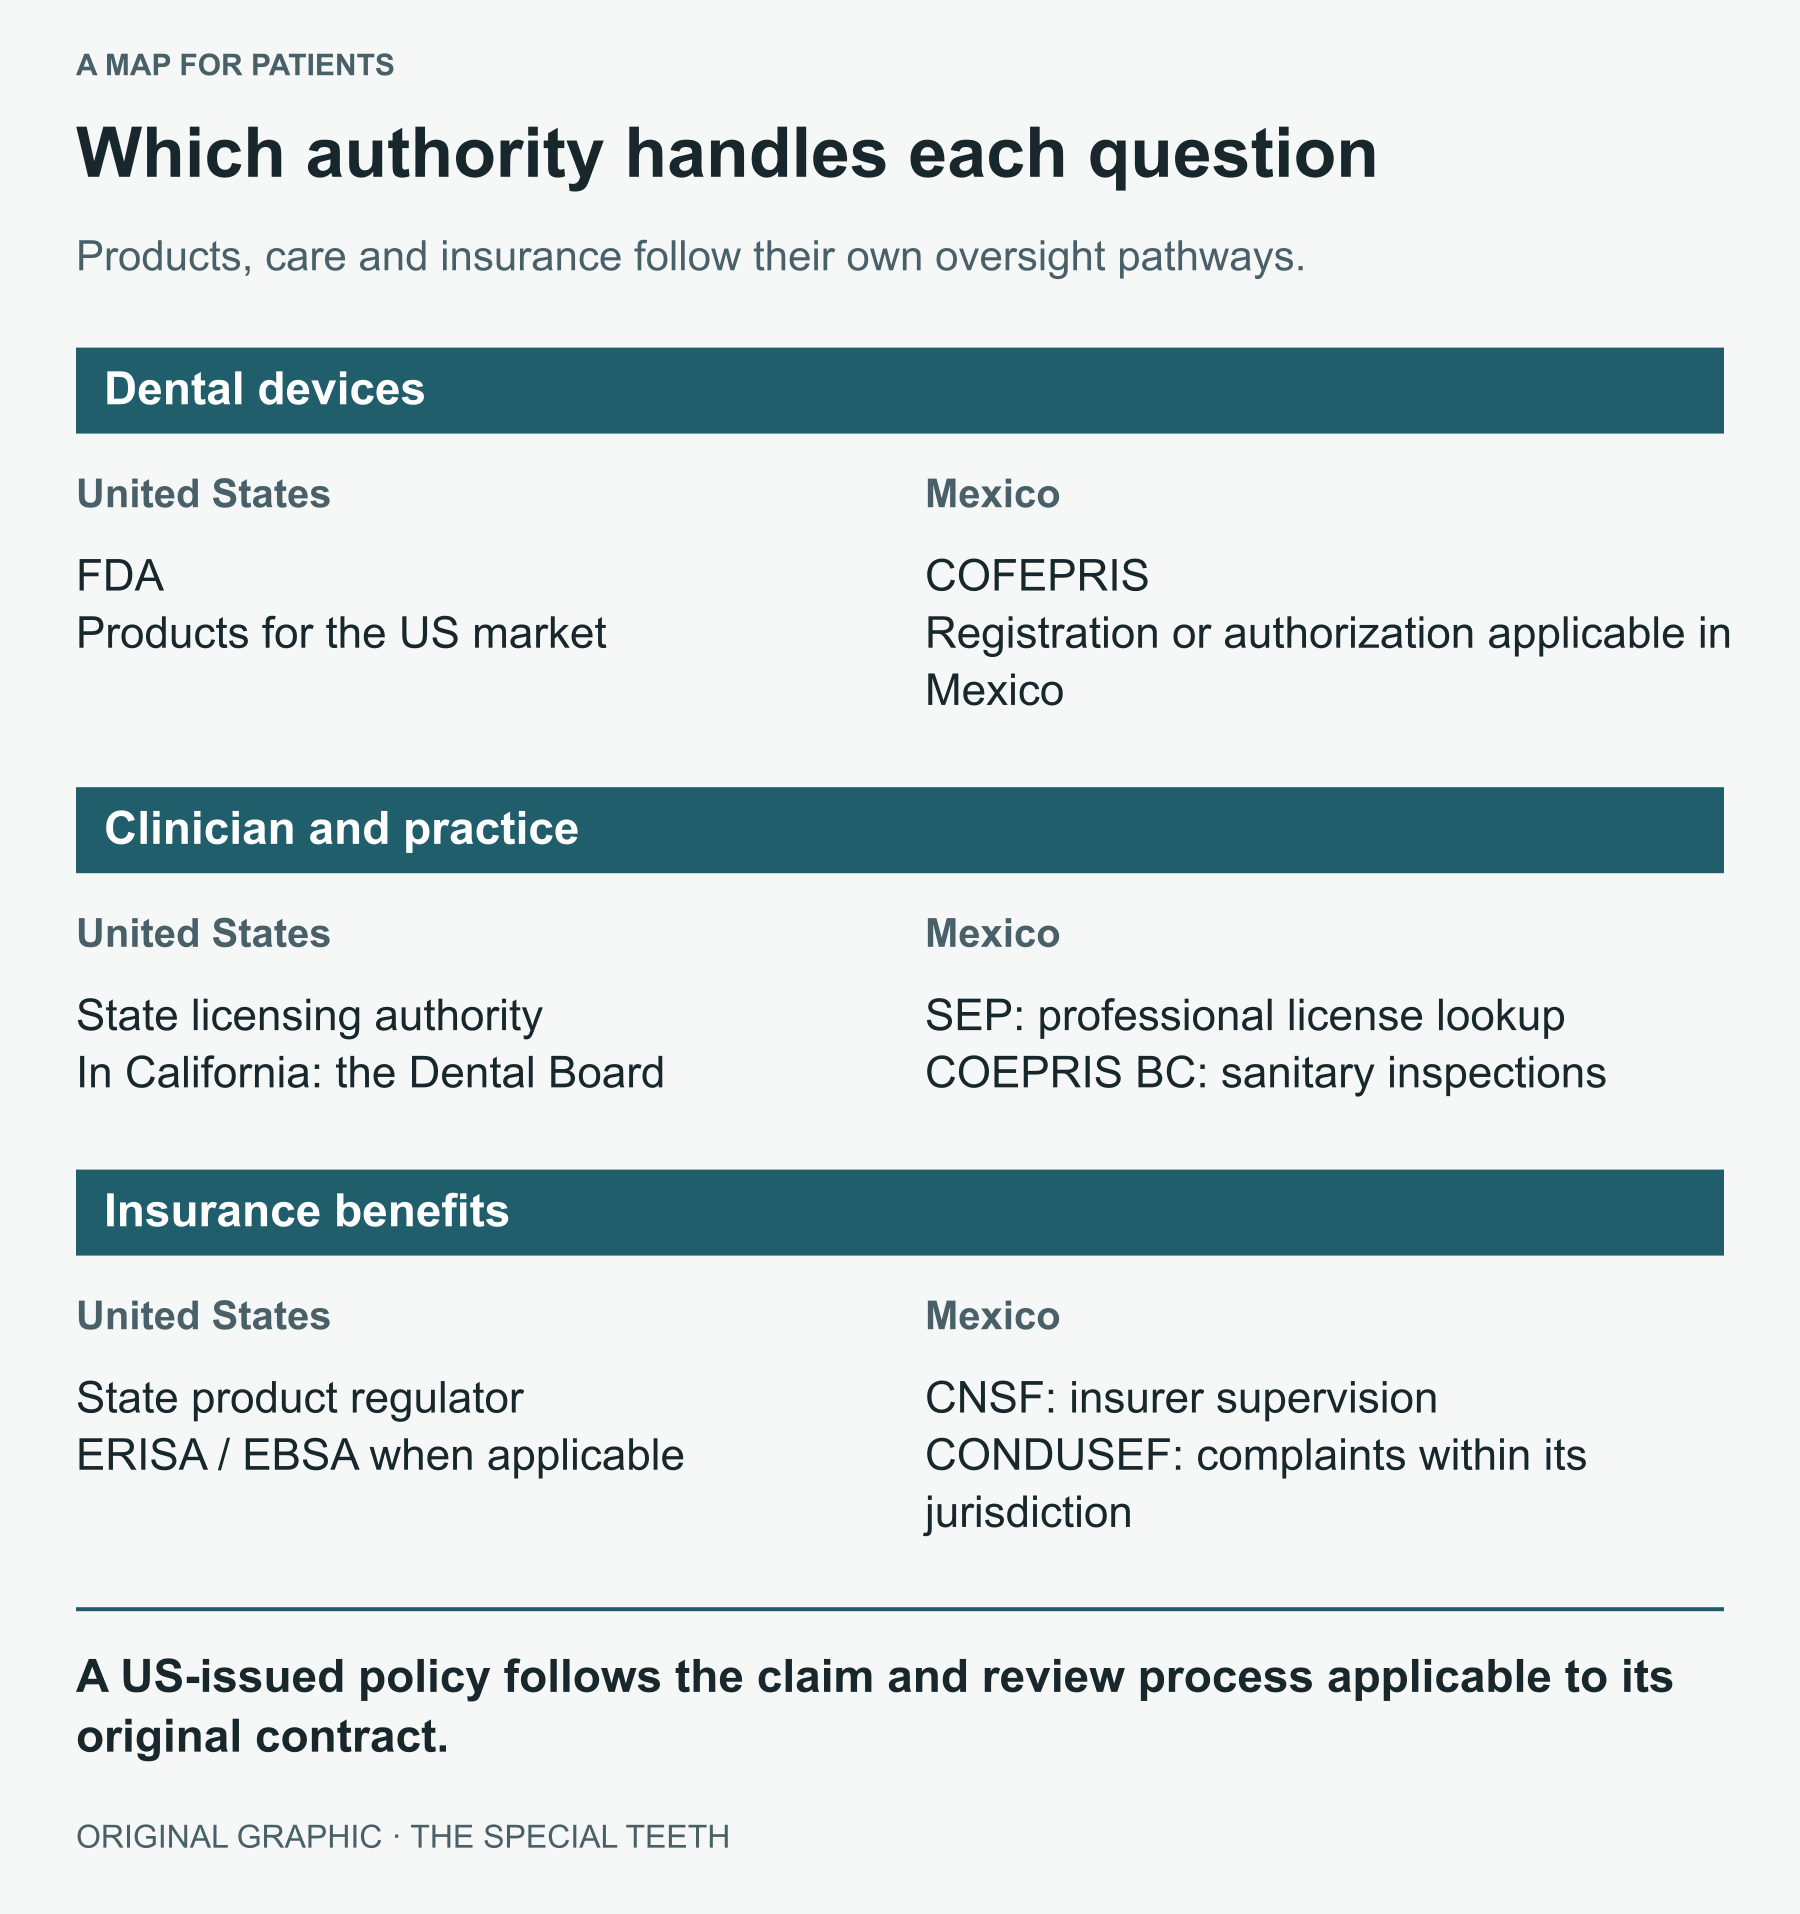
Figure 16 · Editorial graphic
In California, CDI and DMHC divide responsibilities by entity and product. In Mexico, CONAMED offers a clinical-complaint conciliation process subject to its requirements. The dentist’s location and the country where the policy was issued require separate consideration.
For clinical care, Mexico’s National Medical Arbitration Commission, CONAMED, describes a complaint process aimed at conciliation with the provider. Participation and requirements depend on the applicable mechanism. For sanitary concerns about an establishment, COEPRIS BC offers inquiry and reporting channels. Each route addresses a different aspect of a case (CONAMED, 2025; COEPRIS BC, 2025).
Before treatment, agree in writing on the diagnosis, alternatives, estimate, payments, included reviews and what would happen if further intervention became necessary. Keep consent forms, receipts and communications. Those documents support continuing care and clarification of differences about services or financing.
Invoices and claims should identify the clinician, actual treatment location, dates and procedures performed. Accurate documentation supports verification among patient, practice and payer. Consent to treatment, handling of your information and payment authorization deserve explanations you understand before signing.
With responsibilities mapped out, you can plan the trip and continuing care with greater clarity. Continue
16 Dental tourism in Tijuana: visits and follow-up
Tijuana is especially practical when the distance from home allows you to return for checkups and adjustments. Proximity becomes more valuable with treatment completed in stages. Before booking, ask for an estimated number of visits, expected stay and findings that could change the schedule. Allow time for the border crossing and confirm travel documents appropriate to your circumstances.
In orthodontics, continuing appointments are part of care. With implants, planning and restorative stages need to follow clinical progress. Ask which visits require attendance, who will assess recovery and what to do if you develop a problem after returning to the United States.
You can explore quality through specific questions: the clinician’s name and professional license, procedure-related training, documented diagnosis, alternatives, consent, materials, infection control and access to your records. The US Department of State advises investigating provider qualifications and reputation and understanding coverage before receiving care abroad (U.S. Department of State, 2025).
Figure 17 · Stock photograph
Dental instruments arranged on a tray. Photograph by Kaboompics / Karola G on Pexels, used to illustrate a clinical setting.
Kaboompics / Karola G · Photograph source
Related sources
Zemeño-Flores, Cuevas-Contreras and Quiroz-Félix found professional training strengths and opportunities to improve certification and digital tools in their study of dental providers in San Luis Río Colorado. Their regional research supports the value of evaluating individual establishments (Zemeño-Flores et al., 2025).
For continuity, request copies of imaging, procedure records and instructions to share with your US clinician. Agree on a contact for questions and complications. Review travel or medical insurance exclusions relating to planned treatment and its consequences. Recovery instructions should guide the activities you arrange during your stay (Stoney & Leidel, 2025).
Ramírez-Leyva, García González and González Espinoza studied medical tourism in Mexicali through ethnographic work, interviews with 188 patients and document analysis. They emphasize understandable, culturally appropriate communication. For a patient, that means knowing who will provide treatment, what it will cost and how care will continue at home (Ramírez-Leyva et al., 2025).
With visits and follow-up planned, you can organize the portion you will pay directly. Continue
17 Dental financing and interest-free installment offers
If insurance pays part of the treatment, you may need to finance the balance. Without coverage, the same assessment starts with the full estimate. Separate the clinical fee from borrowing costs and decide on a monthly payment that fits alongside essential expenses.
Payment schedules and personal loans
A payment schedule with the practice should specify amounts, dates, and when care will take place. A bank or credit union loan lets you compare annual interest, fees, repayment term, and total paid. The Consumer Financial Protection Bureau recommends reviewing alternatives and costs before accepting medical financing (CFPB, 2023).
Cards and interest free installments
Mexico’s meses sin intereses offers depend on a valid promotion involving the issuer, card and merchant. Confirm whether a US-issued card qualifies, the minimum purchase, currency, total price and monthly payment. CONDUSEF advises checking affordability and terms. Ordinary card acceptance and eligibility for an installment promotion need separate confirmation (CONDUSEF, 2024).
An introductory 0% APR offer and deferred-interest financing follow different rules. With deferred interest, an unpaid balance at the end of the promotion can trigger interest from the purchase date under the agreement. Minimum payments may be too small to pay off the balance in time. CareCredit explains these distinctions; access to its financing requires approval and a participating provider (DeNicola, 2025; CFPB, 2023).
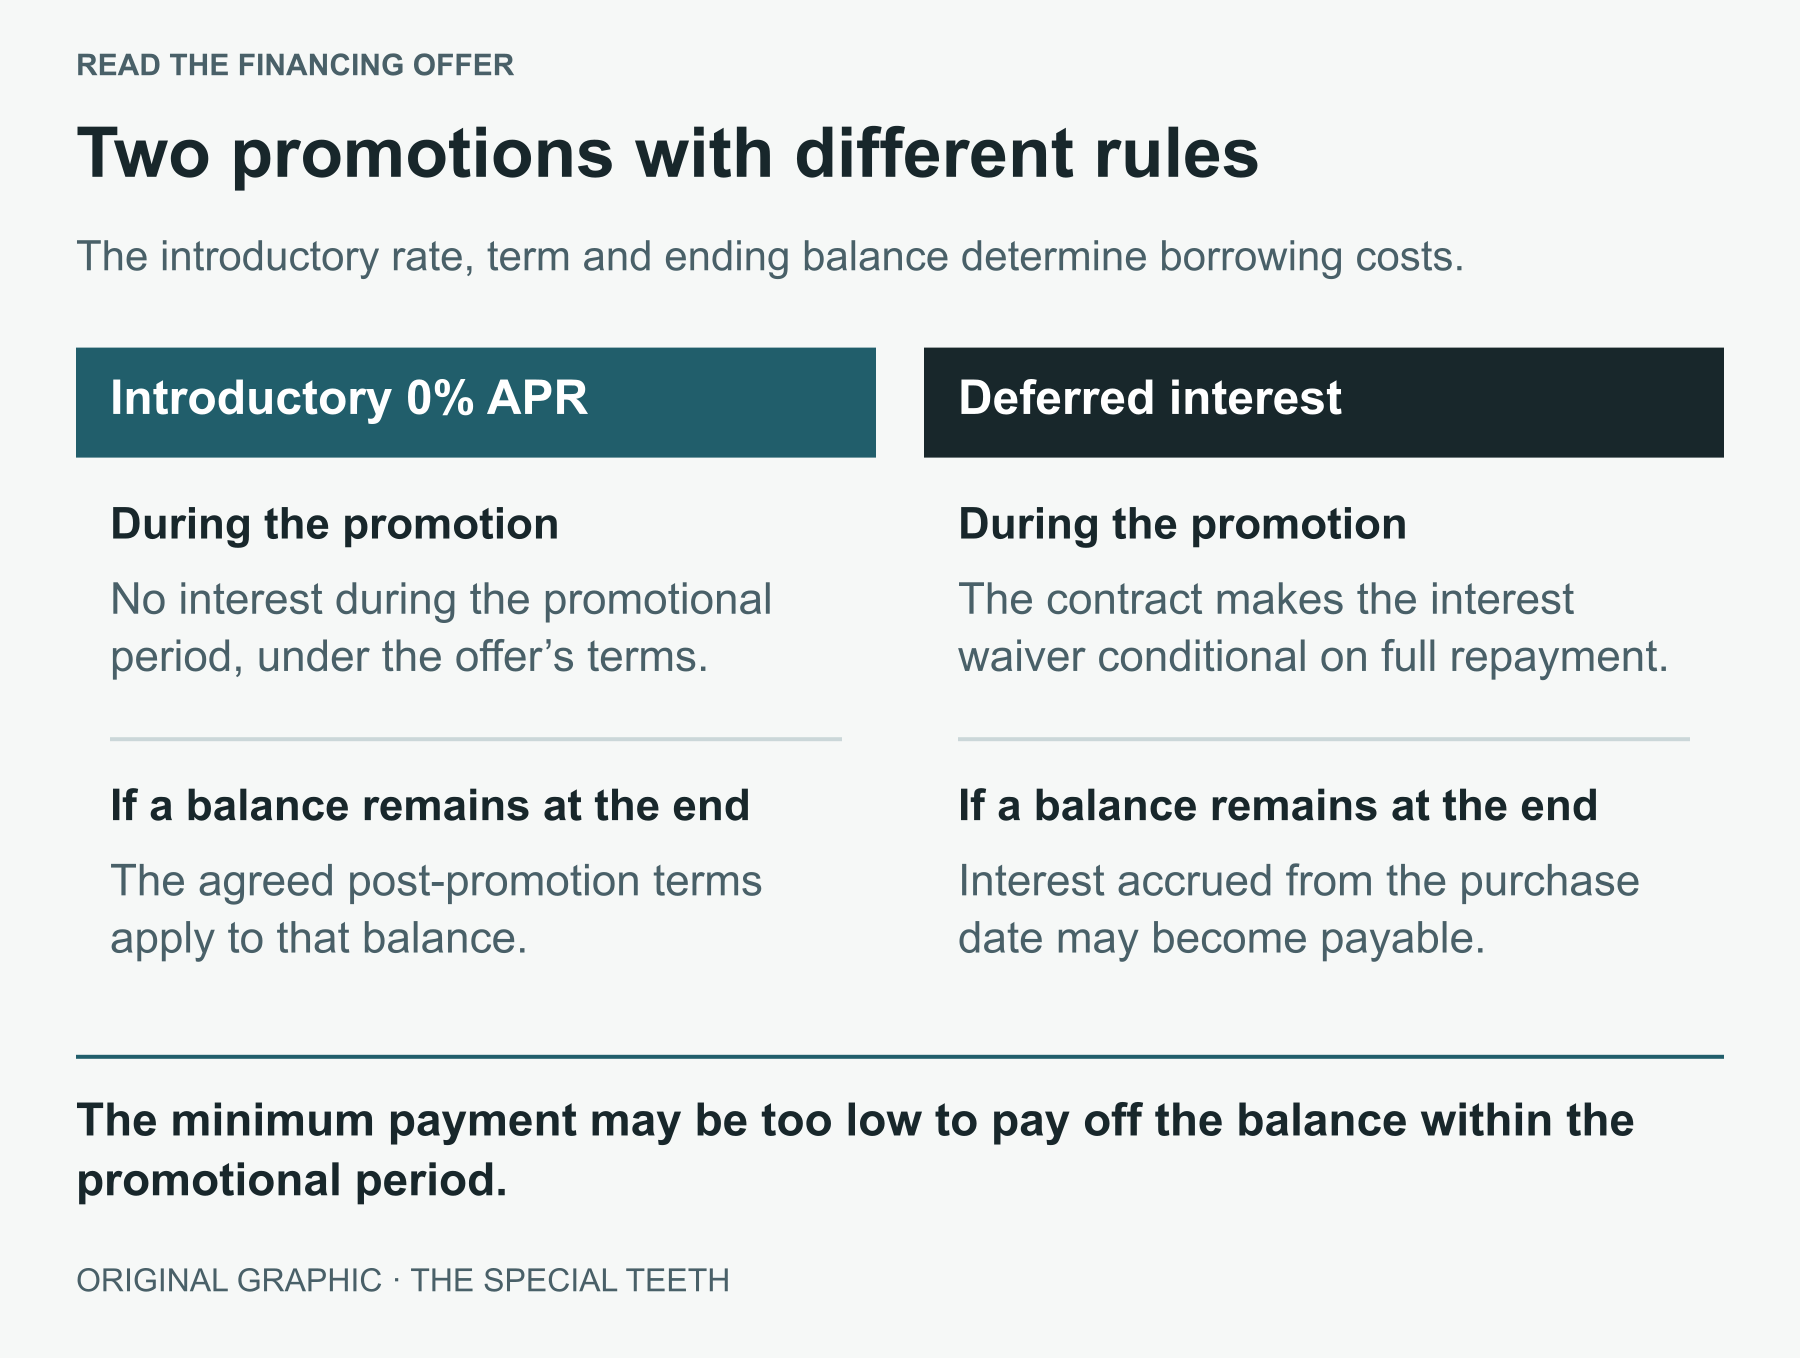
Figure 18 · Editorial graphic
General explanation. Approval, acceptance in Mexico, rate, fees and promotional availability depend on the issuer, product and merchant. Interest-free installment offers require their own confirmation.
Related sources
HSA and FSA funds
An eligible HSA or FSA may help pay qualified dental expenses using tax-advantaged funds. IRS Publications 969 and 502 explain requirements and distinguish eligible dental care from excluded cosmetic expenses. Ask the administrator about Mexican receipts, dates and the amount you can submit; exclude an expense already reimbursed by insurance from a second request for that same amount (IRS, 2026a; IRS, 2026b).
At The Special Teeth: plan your payments and your visit
The Special Teeth offers interest-free installments when the bank, card, and current promotion allow them. Ask our team to confirm the term and conditions applicable to your transaction before the card is charged.
You can also arrange advance payments while planning your trip to Tijuana. Once the agreed amount has been paid in full, we welcome you for your scheduled treatment. Request the payment schedule, total, and terms for coordinating your visit in writing.
To compare options, list installments and the final total in one currency. Check foreign transaction fees and the issuer’s exchange rate. Keep this calculation alongside your clinical estimate and expected insurance benefits when planning the funds needed before your trip.
The decision becomes clearer when the full treatment, available benefits and amount needed to finish care are visible together. Continue
18 Dental insurance and use of care: what the data show
Recent data distinguish enrollment from receiving care. The ADA Health Policy Institute’s September 2026 update, using 2024 data, reports at least one annual dental visit among 52.9% of adults aged 19–64 with private dental insurance, 24.8% with public coverage and 17.0% without coverage. This is an observed association across groups; income, access and population characteristics also matter (American Dental Association, 2026c).
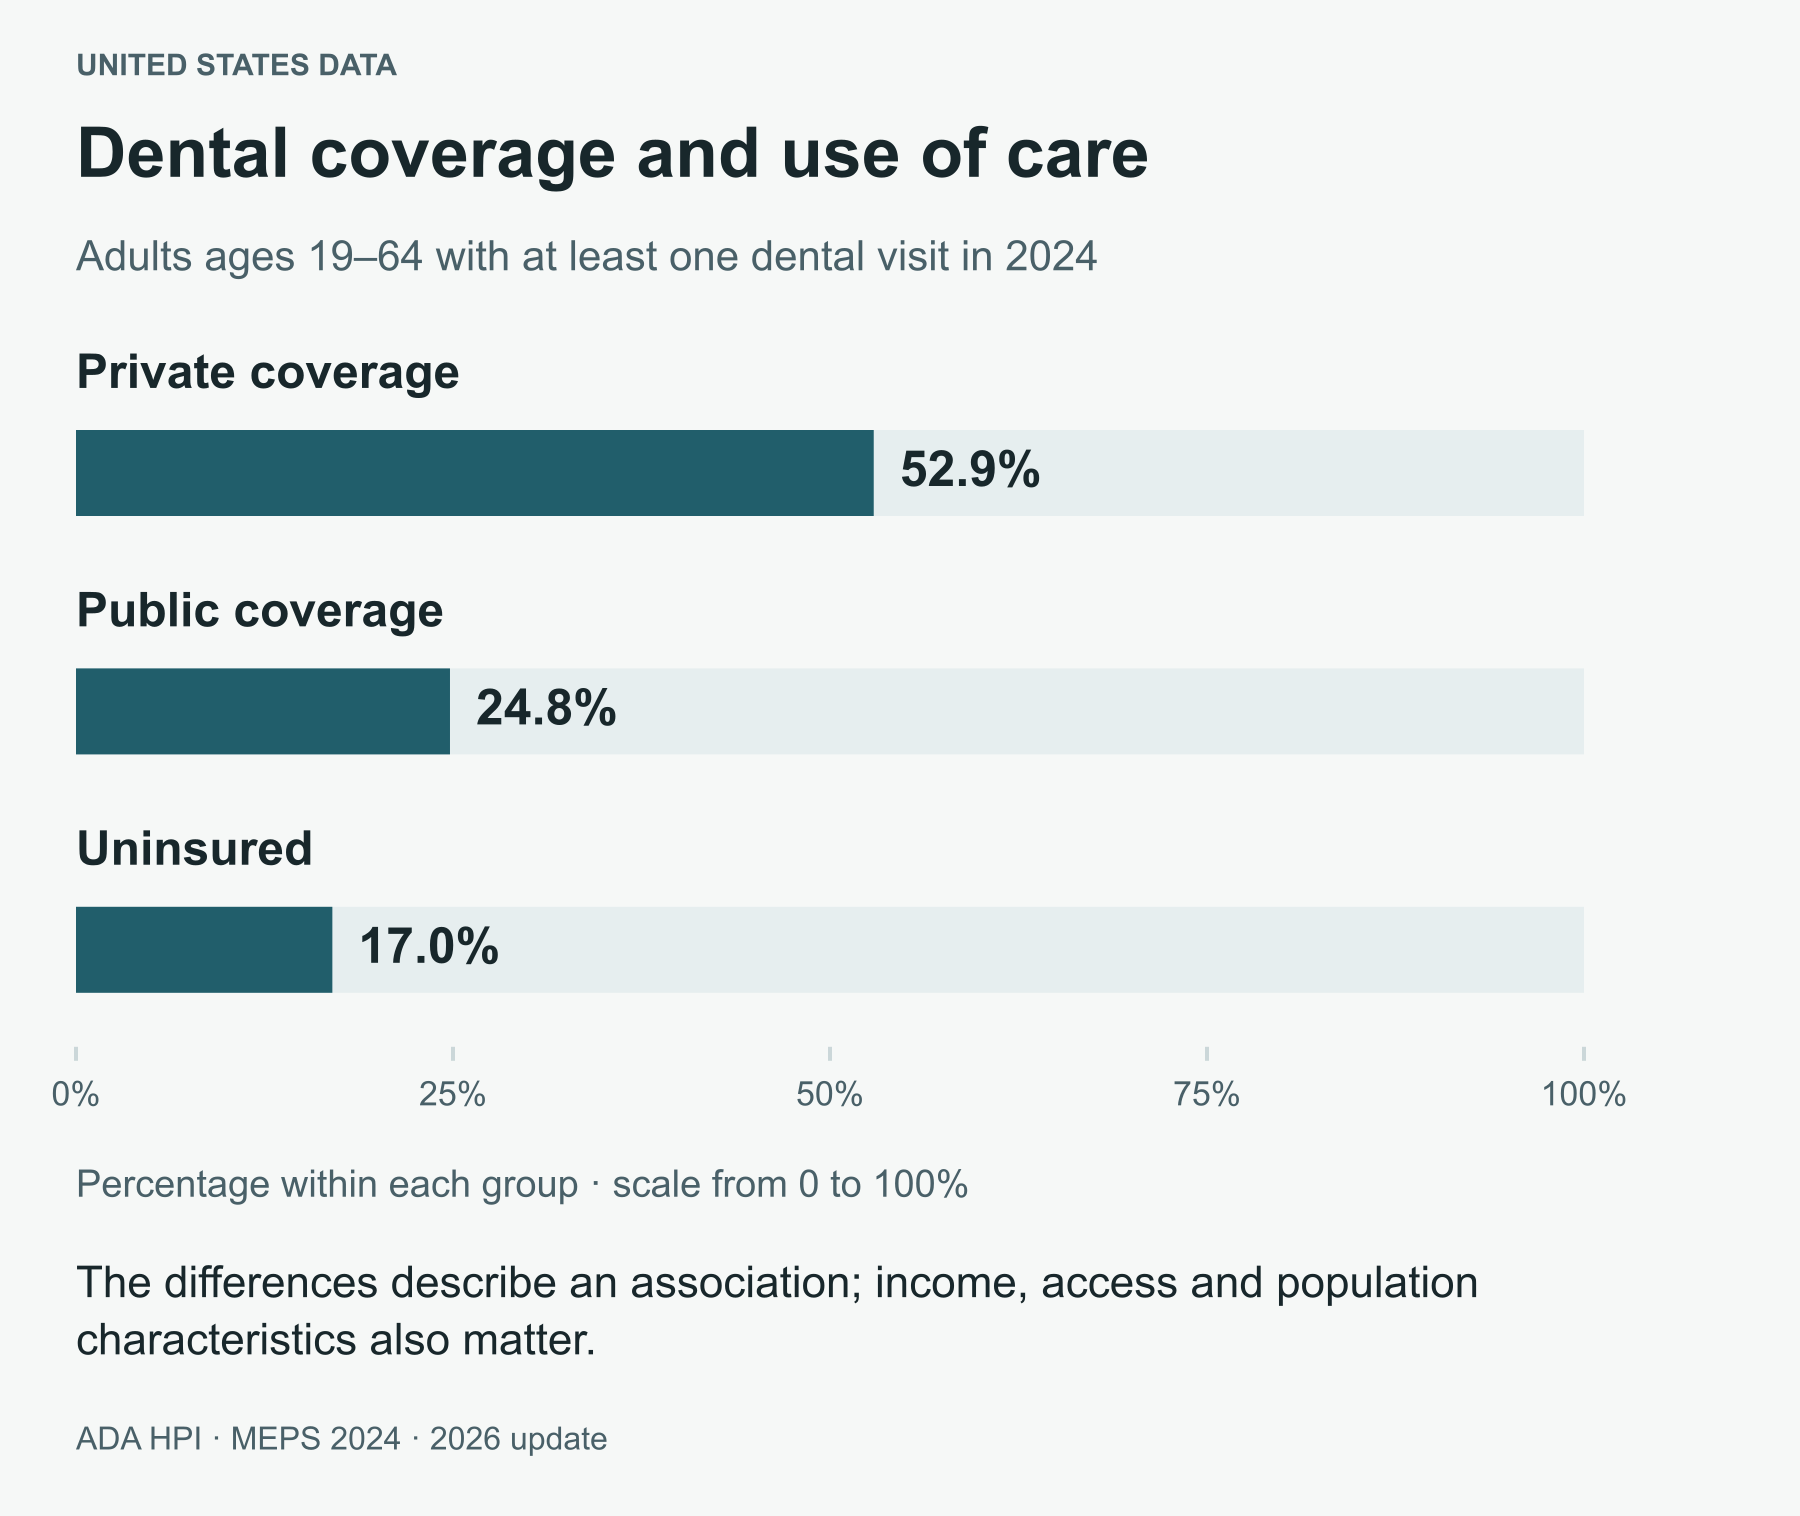
Figure 19 · Editorial graphic
Original graphic using MEPS 2024 data reported by the American Dental Association Health Policy Institute in its September 2026 update, page 16. The comparison describes population groups and does not estimate the causal effect of buying insurance.
Related sources
Read the chart data
| Dental coverage | At least one dental visit in 2024 |
|---|---|
| Private coverage | 52.9% |
| Public coverage | 24.8% |
| Uninsured | 17.0% |
Workplace coverage is changing as well. In May 2026, the National Association of Dental Plans (NADP), an industry association, reported falling overall enrollment and growth in voluntary plans funded mainly by employees, using data through December 2024. It also described a trend toward higher annual maximums. When comparing your benefit, check who funds the premium and how much usable coverage that spending provides (NADP, 2026).
Benefit design is associated with access. In JAMA Health Forum, Nasseh, Singhal, Vujicic and Simon published a cross-sectional study of 1,789 Medicare Advantage enrollees using 2019 data. Higher annual maximums, or no maximum, were associated with better access and fewer unmet dental needs. Published in 2025, the findings apply to that population and period (Nasseh et al., 2025).
Choices also differ by state. A March 2026 Government Accountability Office report found that the three largest insurers accounted for approximately 38% to 98% of enrollment in the dental group markets examined. The analysis covered fully insured, stand-alone private coverage using 2024 data. It supports comparing local products and networks before choosing (GAO, 2026).
For Tijuana, these trends increase the value of a proposal with understandable costs: a patient may be funding more of their own coverage and needs to know how much treatment they can complete. An accessible fee becomes more useful when the contract permits it and follow-up is practical.
These findings offer clues about the future alongside regulatory changes with defined dates and scope. Continue
19 What could change in the years ahead
Adult coverage will continue to require a product review
On May 15, 2026, CMS announced its final benefit and payment parameters rule for 2027, effective July 20, 2026. Within the ACA’s Essential Health Benefit framework, it reverses the policy in the 2025 Payment Notice and prohibits including routine adult dental services as an Essential Health Benefit. Supplemental dental coverage retains its own terms; the change requires distinguishing adult dental benefits from EHB status (Centers for Medicare & Medicaid Services, 2026a).
For Mexican care planned in 2027, the practical step is to review the new benefit-year documents. The decisive information remains the provision permitting international treatment and the recognized payment amount. A domestic benefit change needs its own review before assigning effects to a policy used in Tijuana.
Benefits administration may become more digital
Automation already has documented precedents. In 2023, NADP reported that four of 14 responding companies used artificial intelligence to review X-rays in claims. That figure describes the survey at the time. It identifies a direction of development in benefits administration whose current scope needs confirmation with each company (NADP, 2023).
A reasonable consequence of digital administration would be easier exchange of estimates, imaging and receipts among patients, practices and payers. Making that useful requires readable records, appropriate channels for health information and a review process when disagreements arise. Faster administration can reduce friction; payment remains governed by the contract.
Figure 20 · AI-generated conceptual photograph
AI-generated conceptual photograph about organizing digital records and maintaining continuity of care.
Related sources
Tijuana’s opportunity is in the complete experience
An editorial reading of these trends points to an opportunity for cross-border care: bringing diagnosis, pricing, benefit review and follow-up into one understandable experience. Proximity can support continuity, while local fees can improve affordability. The outcome depends on the individual patient, policy and clinical plan.
Use information for the year in which you will receive treatment. A change in employer, product or network can alter the calculation. Updating coverage before each substantial treatment stage and retaining your records helps turn planning into care you can complete.
The final decision brings together treatment needs, current rules and what your budget can support. Continue
Conclusions
The value of treatment you can complete
Care in Tijuana can combine an accessible local fee, benefits under a policy permitting Mexican treatment and a distance compatible with follow-up. For people living near the border, that combination creates a practical opportunity to receive indicated treatment and return for continuing care.
Confirm the value with a diagnosis, two comparable estimates and an insurance response detailing benefits by procedure. Include travel, later visits and financing in the calculation. Make your choice with information about the clinician, materials and care plan you will receive.
If you are considering The Special Teeth, request an evaluation and share your dental plan details. We work with Aetna and MetLife PPO plans and help you review benefits and the process that applies to your case. Request an itemized treatment proposal, estimated insurance payment, and your balance. You can also ask about interest-free installments available through your bank and advance payments to help organize your visit (The Special Teeth, n.d.-a).
Sources and scope
This patient education feature draws on literature from 2022–2026 and official plan documents. Commercial or guidance pages without an editorial date are identified as undated and were checked on October 17, 2026; data dates are stated where available. Ramos and Cuamea’s study was used through its publisher’s abstract. US price references come from commercial research commissioned by CareCredit; The Special Teeth’s figures are the practice’s public advertisements and require an individual estimate. Calculation examples are hypothetical. Plan terms and clinical assessment determine each patient’s benefits and treatment. Regulatory information was checked as of October 17, 2026, with each measure described within its applicable market and framework. Future perspectives are presented as editorial interpretation, separately from adopted rules. The practice directly confirmed its information on PPO benefits assistance, bank-dependent interest-free installments, and advance payments on October 18, 2026.
References
Aetna. (n.d.).
Dental plans made for you
.
Retrieved October 17, 2026, from
https://www.aetna.com/individuals-families/buy-dental-coverage.html
Aetna. (2023, November).
More smiles
[Aetna International Dental PPO; flyer 2675364-01-01]
.
https://www.aetna.com/content/dam/aetna/pdfs/aetna-international/memberkit/Flyer-Mem-Dental-PPO-en.pdf
Aetna. (2026).
Aetna Dental
[2026 FEDVIP brochure]
.
https://www.opm.gov/healthcare-insurance/healthcare/plan-information/plans/pdf/2026/brochures/02AP-01.pdf
American Dental Association. (n.d.-a).
ADA guidance on coordination of benefits
.
Retrieved October 17, 2026, from
https://www.ada.org/resources/practice/dental-insurance/ada-guidance-on-coordination-of-benefits
American Dental Association. (n.d.-b).
Types of dental plans
.
Retrieved October 17, 2026, from
https://www.ada.org/resources/practice/dental-insurance/dental-plan-overview/
American Dental Association. (2026a, May).
Dear ADA: Out-of-network billing
.
ADA News.
https://adanews.ada.org/ada-news/2026/may/dear-ada-out-of-network-billing
American Dental Association. (2026b, August).
Dear ADA: Insurance premiums
.
ADA News.
https://adanews.ada.org/ada-news/2026/august/dear-ada-insurance-premiums/
American Dental Association. (2026c, September).
National trends in dental care use, dental insurance coverage, and cost barriers
.
https://www.ada.org/-/media/project/ada-organization/ada/ada-org/files/resources/research/hpi/national_trends_dental_use_benefits_barriers_2026.pdf?hash=A677CC5ABF80C3CAACD233E2AC4C3489&rev=08aa8ee393c24290b90e7fdb76936432
California Department of Insurance. (2025, January 31).
Health insurer dental coverage compliance California Insurance Code section 10120.41
[Notice on AB 1048 compliance]
.
https://www.insurance.ca.gov/0250-insurers/0300-insurers/0200-bulletins/bulletin-notices-commiss-opinion/upload/Notice-Health-Insurer-Dental-Compliance-Cal-Ins-Code-10120-41.pdf
California Department of Managed Health Care. (n.d.).
File a complaint
.
Retrieved October 17, 2026, from
https://www.dmhc.ca.gov/FileaComplaint.aspx
Centers for Medicare & Medicaid Services. (n.d.).
Dental coverage in the Health Insurance Marketplace
.
HealthCare.gov.
Retrieved October 17, 2026, from
https://www.healthcare.gov/coverage/dental-coverage/
Centers for Medicare & Medicaid Services. (2026a, May 15).
HHS Notice of Benefit and Payment Parameters for 2027 final rule
.
https://www.cms.gov/newsroom/fact-sheets/hhs-notice-benefit-payment-parameters-2027-final-rule
Centers for Medicare & Medicaid Services. (2026b, September).
Medicare & you 2027
[CMS Publication No. 10050]
.
https://www.medicare.gov/publications/10050-medicare-and-you0.pdf
Cigna Healthcare. (n.d.).
Affordable dental insurance plans
[Reference rates dated July 2025]
.
Retrieved October 17, 2026, from
https://www.cigna.com/individuals-families/shop-plans/dental-insurance-plans
Comisión Estatal para la Protección contra Riesgos Sanitarios de Baja California. (2025, May 6).
Realiza COEPRISBC jornada intensiva de registro al REPSSABI
.
https://www.coeprisbc.gob.mx/detalleblog.php?id=453969
Comisión Federal para la Protección contra Riesgos Sanitarios. (2025, August 21).
Dispositivos médicos
.
https://www.gob.mx/cofepris/acciones-y-programas/dispositivos-medicos-403833
Comisión Nacional de Arbitraje Médico. (2025, December 5).
Atención de quejas médicas
.
https://www.gob.mx/conamed/es/acciones-y-programas/queja-medica-para-conciliacion-ante-la-conamed?idiom=es
Comisión Nacional de Seguros y Fianzas. (n.d.).
Preguntas frecuentes sobre la CNSF
.
Retrieved October 17, 2026, from
https://www.cnsf.gob.mx/cnsf/revista/Documentos%20compartidos/Preguntas%20frecuentes%20CNSF.pdf?web=1
Comisión Nacional de Seguros y Fianzas. (2025, February 24).
Quejas contra ajustadores, ante la CNSF
.
https://www.gob.mx/cnsf/acciones-y-programas/quejas-contra-ajustadores
Comisión Nacional para la Protección y Defensa de los Usuarios de Servicios Financieros. (2024, November).
Se acerca el Buen Fin
.
Revista Proteja su Dinero.
https://revista.condusef.gob.mx/usuario-inteligente/tu-bolsillo/2024/11/buen-fin-2/
Consumer Financial Protection Bureau. (2023, May 8).
What should I know about medical credit cards and payment plans for medical bills?
DeNicola, L. (2025, September 12).
What is a promotional balance on a credit card?
CareCredit.
https://www.carecredit.com/well-u/financial-health/what-is-promotional-balance/
Dental coverage disclosures, A.B. 952, 2023–2024 Reg. Sess., ch. 125 (Cal. 2023).
https://leginfo.legislature.ca.gov/faces/billNavClient.xhtml?bill_id=202320240AB952
Internal Revenue Service. (2026a, February 11).
Health savings accounts and other tax-favored health plans
[Publication 969 for 2025 returns]
.
https://www.irs.gov/pub/irs-pdf/p969.pdf
Internal Revenue Service. (2026b, February 5).
Medical and dental expenses
[Publication 502 for 2025 returns]
.
https://www.irs.gov/pub/irs-pdf/p502.pdf
Kennedy, A.-M. (2026, September 11).
Root canal cost and procedure guide
.
CareCredit.
https://www.carecredit.com/well-u/health-wellness/what-is-a-root-canal/
MetLife. (n.d.).
MetLife TakeAlong Dental
.
Retrieved October 17, 2026, from
https://www.metlife.com/insurance/dental-insurance/takealongdental/
MetLife. (2025a, September 21).
Dental claims: How to file one and what to expect
.
https://www.metlife.com/oralfitnesslibrary/dental-insurance/dental-claims-how-to-file-one-and-what-to-expect/
MetLife. (2025b).
Dental insurance
[DHMO benefit overview]
.
https://www.metlife.com/content/dam/metlifecom/us/homepage/regional/dental-insurance-hmo-benefit-overview.PDF
MetLife. (2025c).
Dental insurance
[PPO benefit overview]
.
https://www.metlife.com/content/dam/metlifecom/us/homepage/regional/dental-insurance-ppo-benefit-overview.PDF
MetLife. (2025d, September 21).
What does dental insurance cover?
https://www.metlife.com/oralfitnesslibrary/dental-insurance/what-does-dental-insurance-cover/
MetLife. (2026a, January 28).
A comprehensive guide to dental coverage for all ages
.
https://www.metlife.com/oralfitnesslibrary/dental-insurance/a-comprehensive-guide-to-dental-coverage-for-all-age/
MetLife. (2026b).
The MetLife federal dental plan
[2026 FEDVIP brochure updated in May]
.
https://fedvip.metlife.com/content/dam/metlifecom/us/homepage/federal-dental/2024/dental/2026-MetLife-Dental-Brochure-5-5-2026-JN-FINAL.pdf
MetLife. (2026c, March 31).
What is dental insurance & how does it work?
https://www.metlife.com/stories/dental-insurance/what-is-dental-insurance/
Nasseh, K., Singhal, A., Vujicic, M., & Simon, L. (2025).
Benefit design and access to dental care among seniors with Medicare Advantage dental benefits.
JAMA Health Forum, 6
(1)
, Article e245123.
https://doi.org/10.1001/jamahealthforum.2024.5123
National Association of Dental Plans. (2023, May 2).
Plans using or considering using A.I. in claims processing, per NADP research
.
https://www.nadp.org/plans-using-or-considering-using-a-i-in-claims-processing-per-nadp-research/
National Association of Dental Plans. (2026, May 18).
NADP publishes State of the Dental Benefits Market Report: Provider and patient benefits rose; dental plan enrollment fell in 2024
.
https://www.nadp.org/nadp-provider-patient-benefits-rose-dental-plan-enrollment-fell-in-2024/
Organisation for Economic Co-operation and Development. (2025).
Health at a glance 2025: OECD indicators
.
https://doi.org/10.1787/8f9e3f98-en
Ramos, K., & Cuamea, O. (2023).
Dental tourism: Factors influencing travelers’ revisit intention to the Mexican border.
International Journal of Tourism Cities, 9
(3)
, 806–831.
https://doi.org/10.1108/IJTC-03-2023-0046
Ramírez-Leyva, F. M., García González, J., & González Espinoza, M. (2025).
Desarrollo del turismo médico en la frontera norte de México y estrategias de comunicación.
Revista de Comunicación y Salud, 15
, 1–19.
https://doi.org/10.35669/rcys.2025.15.e368
Rosenfeld, J. (2024, November 15).
How much do dental crowns cost? Pricing and insurance guide
.
CareCredit.
https://www.carecredit.com/well-u/health-wellness/dental-crown-cost-dental-crown-financing/
Secretaría de Educación Pública. (2025).
Boletín 311. Presenta SEP nuevo portal del Registro Nacional de Profesionistas y la emisión de cédulas en 68 lenguas indígenas del país
.
https://www.gob.mx/sep/prensa/boletin-311-presenta-sep-nuevo-portal-del-registro-nacional-de-profesionistas-y-la-emision-de-cedulas-en-68-lenguas-indigenas-del-pais?idiom=es
Secretaría de Turismo. (2025).
Programa Sectorial de Turismo 2025–2030
.
Diario Oficial de la Federación.
https://sidof.segob.gob.mx/notas/docFuente/5767922
Secretaría de Turismo de Baja California. (2022).
Programa Sectorial de Turismo 2022–2027
.
https://www.bajacalifornia.gob.mx/Documentos/coplade/planeacion/programas/Programa%20Sectorial%20de%20Turismo.pdf
SIMNSA. (2026).
Evidence of coverage and disclosure form for large group plans
.
https://simnsa.com/wp-content/uploads/2026/01/SIMNSA_Large-Group-EOC-v2026.pdf
State of California. (2025, December 29).
Dental Board of California
.
CA.gov.
https://www.ca.gov/departments/24/
Stoney, R. J., & Leidel, L. (2025, April 23).
Medical tourism. In
CDC Yellow Book 2026
. Centers for Disease Control and Prevention.
https://www.cdc.gov/yellow-book/hcp/health-care-abroad/medical-tourism.html
The Special Teeth. (n.d.-a).
Aetna and MetLife PPO dental insurance in Tijuana
.
Retrieved October 17, 2026, from
https://thespecialteeth.com/en/dental-insurance-aetna-metlife-ppo/
The Special Teeth. (n.d.-b).
Dentist in Tijuana
.
Retrieved October 17, 2026, from
https://thespecialteeth.com/en/
U.S. Department of Labor. (n.d.).
Understanding your fiduciary responsibilities under a group health plan
.
Retrieved October 17, 2026, from
https://www.dol.gov/node/63394
U.S. Department of Labor. (2026, July).
Health plan investigations
[EBSA enforcement manual]
.
https://www.dol.gov/agencies/ebsa/about-ebsa/our-activities/enforcement/oe-manual/health-plan-investigations
U.S. Department of State. (2025, August 11).
Medicine and health
.
https://travel.state.gov/en/international-travel/planning/guidance/medicine-health.html
U.S. Food and Drug Administration. (2024, October).
Endosseous dental implants and endosseous dental implant abutments—Performance criteria for Safety and Performance Based Pathway
[Final guidance for industry and FDA staff]
.
https://www.fda.gov/regulatory-information/search-fda-guidance-documents/endosseous-dental-implants-and-endosseous-dental-implant-abutments-performance-criteria-safety-and
U.S. Government Accountability Office. (2026, March 9).
Private dental and vision insurance: Market concentration varied among states
[Report GAO-26-107787]
.
https://www.gao.gov/products/gao-26-107787
Zemeño-Flores, S. G., Cuevas-Contreras, T. J., & Quiroz-Félix, J. (2025).
Turismo dental trasfronterizo México-EUA: El perfil de la oferta en San Luis Rio Colorado, Sonora.
RITUR Revista Iberoamericana de Turismo, 15
(1)
, 50–67.
https://doi.org/10.28998/ritur.V15.N1.A2025.pp50-67.18627